Best Equipment Financing: Top Vendor Programs for Dealers

best equipment financing

Best Equipment Financing: Top Vendor Programs for Dealers

Best equipment financing, from a dealer’s perspective, is not the loan or lease itself. It is a vendor program that clears customers fast, covers everything tied to the sale, and pays the dealer in full without a collections cycle. 

Dimension Funding has run these programs for equipment and software sellers since 1978, and its equipment vendor program clears most applicants up to $250,000 without financial statements.

Above that threshold, expect a tax return or financial statement in the file, which is usually where turnaround stretches from hours to days. The program covers the equipment, delivery, installation, training, and outside vendor costs in one approval, structured as a loan or a lease. 

Dealers weighing vendor financing options are really comparing speed, paperwork, coverage, and sales support.

What the Best Vendor Financing Programs Have in Common

Dealers evaluating a finance partner tend to compare them the way they compare a distributor, on speed, coverage, and how much of the sales process the partner takes off their plate. A partner that asks for two years of financial statements on a routine transaction is not solving the dealer’s real problem: closing the sale before the buyer calls a competitor.

A vendor finance program is a partnership between a manufacturer, dealer, or distributor and a lender to offer financing at the point of sale. The vendor closes faster, and the lender gets a steady stream of originated business, according to equipment finance technology firm Uptiq. 

The most effective vendor programs usually have these five things in common:

  • Fast approvals, decisions in hours, not days, for standard deals
  • A clear “application-only” threshold so simple deals don’t get stuck in paperwork
  • Full-scope coverage that includes delivery, installation, and training costs
  • Flexible options that let you offer both loans and leases in one application
  • Ready-to-use marketing materials and calculators your sales team can use mid-conversation

Why Dealers Are Building Financing Into Every Quote

Forrester Research found that businesses offering point of sale financing saw a 32 percent increase in sales and a 75 percent increase in average order value, a pattern often cited for equipment sellers who put financing in front of the buyer at the moment of decision, according to Forbes. A buyer who has to leave the lot to sort out financing on their own does not always come back.

The finance industry’s own numbers back this up. Captive and vendor focused finance companies grew new business volume 5.9 percent in 2024, while bank lenders saw new business volume decline 1.3 percent, according to the Equipment Leasing and Finance Association’s 2025 Survey of Equipment Finance Activity. Independent finance companies grew 17.7 percent over the same period, faster than either banks or captives.

Application Only Approval Changes the Sales Conversation

Dimension Funding’s equipment vendor program clears qualified applicants up to $250,000 without financial statements, and software vendor programs extend that same threshold to $500,000. Most approvals come back within a few hours of a submitted quote, and electronic applications paired with DocuSign let a buyer sign from a phone before leaving the showroom or job site.

That speed changes what happens next. A buyer comparing two dealers will often pick the one who can answer “how do I pay for this” on the spot, not the one who says to call a bank and follow up next week.

What a Strong Vendor Program Covers Beyond the Equipment

Structuring the Deal as a Loan or a Lease

On paper, equipment financing sounds like it only covers the machine. In practice, a strong vendor program also picks up freight, rigging, on-site installation, operator training, and third-party integration work, all inside the same approval and the same monthly payment. A buyer paying installation out of pocket while financing only the invoice price is doing math on two separate bills instead of one.

Terms typically run 12 to 60 months, and the same application can be structured as a fixed-term loan or an equipment lease. A lease often suits a buyer who would rather expense the payment than carry the asset on the balance sheet; a loan puts both the asset and the obligation on the books from day one. That choice is often what separates a program a dealer’s team uses regularly from one that sits unused in a sales folder.

Marketing and Sales Support Behind the Financing

A financing partner that only processes paperwork leaves the sales team to explain and sell the financing itself, which rarely happens with any consistency. Dimension Funding’s vendor partner toolkit includes co-branded literature, a financing widget that adds a payment calculator and online credit application to the dealer’s own website, and material reps can hand a buyer mid conversation.

A rep who can pull up a payment estimate on a tablet mid-pitch is having a different conversation than one who promises someone will call back tomorrow.

Pairing Section 179 With Deferred Payment Offers

The 2025 IRS Section 179 deduction allows businesses to write off up to $2,500,000 in qualifying equipment and software purchases in the year they are placed in service, with a $4,000,000 spending cap before the deduction phases out, per Dimension Funding’s Section 179 breakdown. This is general information, not legal or tax advice, and buyers should confirm details with their own tax professional.

Pairing that deduction with a 90 day deferred payment structure, so the buyer installs and starts using the equipment before the first payment comes due, gives dealers a concrete reason to close before year end instead of waiting on next year’s budget.

Setting Up a Vendor Financing Program at Your Dealership

None of this works if the sales team does not use it, which is why Dimension Funding pairs its vendor programs with an account team that tends to stay in place. 

Much of its sales staff has been with the company 20 years or more, so the person handling your account this year is often the same one five years from now. Becoming a vendor partner does not require an existing relationship or a minimum transaction volume to start.

If your dealership is quoting equipment or software and losing deals to the “how do I pay for this” objection, applying to become a vendor partner is the direct next step. The team can also walk you through the payment calculator your sales staff would use with prospects, and you can reach Dimension Funding at 1.800.755.0585 or Sales@DimensionFunding.com.

Frequently Asked Questions

What is a vendor financing program for equipment dealers?

A vendor financing program is an arrangement between an equipment or software seller and a finance company that lets the seller offer financing directly at the point of sale. The finance partner handles underwriting and funding, so the dealer keeps control of the sales conversation instead of sending the buyer off to arrange financing on their own.

How fast can a customer get approved through a dealer’s financing program?

For deals under a program’s application-only threshold, approval can come back within a few hours of submitting a quote. Once a transaction requires financial statements, the review typically takes a few business days instead of a few hours.

Does the financing cover delivery and installation, or just the equipment cost?

Yes, a program built for the full transaction finances freight, installation, and training alongside the equipment itself. For software purchases, that same structure typically rolls implementation work and license fees into a single payment.

Can a dealer offer both leases and loans through the same program?

Most vendor programs let the buyer choose between a fixed-term loan or an equipment lease within the same application. A lease suits a buyer who wants the payment to run through the income statement, while a loan puts the asset and the debt directly on the books.

What is the difference between a captive finance company and a third party vendor financing partner?

A captive finance company is a lender wholly owned by the equipment manufacturer, built to finance only that manufacturer’s products. A third party partner works across multiple dealers and equipment categories, which often means more flexibility in how a program is structured and a faster path to onboarding for dealers outside a manufacturer’s in-house finance arm.

Does becoming a vendor partner cost the dealer anything to join?

Becoming a vendor partner does not carry an upfront cost for the dealer in a standard program. The finance partner earns through the transactions it originates, while the dealer gets faster closes and marketing support at no separate charge.

How does the Section 179 deduction fit into a vendor financing pitch?

The 2025 Section 179 deduction lets businesses write off up to $2,500,000 in qualifying equipment and software purchases in the year of purchase. Raising that figure alongside a financing quote gives a buyer a reason to close before their fiscal year ends rather than pushing the purchase into next year’s budget, though they should confirm specifics with a tax professional.

Finance Commercial Equipment: Smart Strategies for Growing Companies

finance commercial equipment (1)

Finance Commercial Equipment: Smart Strategies for Growing Companies

A company lands a contract that finally justifies the new equipment it has needed for a year, then finds out the bank loan process takes weeks and calls for years of financial statements it would rather not hand over. 

By the time approval comes through, the window to actually use that contract to grow may have narrowed. This is the exact moment more companies choose to finance commercial equipment instead of waiting on a traditional bank loan.

Why Growing Companies Finance Commercial Equipment Instead of Paying Cash

Paying cash for a forklift, a commercial oven, or a fleet of service vehicles feels simple, but it ties up money a growing company usually needs somewhere else, payroll, inventory, marketing, or the next opportunity that shows up before the current one is even finished paying for itself.

Financing spreads that cost into a single fixed monthly payment instead of one large outlay. That keeps cash available for the parts of the business that do not have a financing option, while the equipment itself starts generating revenue right away. For a company adding capacity to handle growth, that timing matters more than the interest rate.

The companies that get the most out of this approach tend to treat equipment financing as a standing part of how they grow, not a one-time fix for a single purchase. 

Every time capacity becomes the limiting factor, whether that is a second delivery vehicle, another piece of production equipment, or a system upgrade, the same question comes up: save up and buy it outright later, or put it to work now while the payment stays predictable and cash keeps moving.

Financing vs. Leasing: Which Fits Your Strategy

Both options get equipment onto your floor without draining your bank account, but they work differently depending on what the business needs most.

Equipment Financing (Loans)

With an equipment loan, the business owns the equipment from day one and builds equity in it as the loan gets paid down. Payments are fixed, terms commonly run up to 60 months, and once the loan is paid off, the equipment is fully owned with no further payments or lease-end decisions to make.

Equipment Leasing

A lease can be structured a couple of different ways, and the structure changes what it does for the business. A capital lease looks and functions much like a loan, letting the business claim depreciation and take advantage of the same tax treatment as ownership. 

An operating lease usually does not appear as debt on the balance sheet, which matters for a company watching its debt to credit ratio, though it also affects the tax benefits available.

Because the right structure depends on a company’s specific financials and goals, this is worth a conversation with an accountant or tax advisor before deciding, not just a rate comparison.

Why Application-Only Financing Speeds Everything Up

The biggest practical difference between a bank and an equipment finance company is usually the paperwork. Application-only financing up to $250,000 does not require financial statements, tax returns, or the kind of underwriting package a bank typically wants before approving a commercial loan.

That difference shows up in speed. Approvals often come back within 24 hours, and funding is commonly available within 48 hours of approval. For a company that needs equipment running before a busy season starts or a new contract kicks off, that turnaround can matter as much as the payment amount itself.

Using Section 179 to Lower the Real Cost

Financed equipment is not just easier to acquire, it can also reduce what a company owes in taxes for the year it goes into service. Under Section 179 of the IRS code, businesses can elect to deduct the full cost of qualifying equipment and off-the-shelf software in the year it is purchased, rather than depreciating it slowly over several years.

For 2025, the deduction limit sits at $2,500,000, with a $4,000,000 spending cap before the available deduction starts phasing out dollar for dollar. Bonus depreciation, generally applied once that spending cap is reached, is set at 100 percent for the year. 

Both new and used equipment can qualify, as long as it is used for business more than half the time and placed in service within the tax year. These figures are adjusted for inflation periodically, so it is worth confirming the current year’s numbers before assuming last year’s limits still apply.

Financing does not disqualify equipment from this treatment. In many cases a business can finance the purchase, keep its cash on hand, and still take the full deduction in the same year, which is part of why financing and Section 179 tend to get mentioned together. 

Because the details depend on a company’s specific tax situation, this is worth confirming with an accountant before filing, not assumed from a blog post. 

Dimension Funding keeps an updated breakdown of the current year’s Section 179 deduction limits for anyone comparing the numbers before a purchase.

What It Takes to Qualify

Growing companies often assume equipment financing requires the same credit profile as a bank loan, which is not usually the case. Approval is based more on the overall picture, time in business, revenue trends, and how the equipment itself supports the company’s plans, than on a single credit score cutoff.

Credit profiles ranging from strong to marginal are commonly considered rather than automatically declined, and a newer or less established company is not necessarily locked out the way it might be with a traditional bank. 

That does not mean every applicant is approved for every amount, but it does mean a less than perfect credit history is not automatically disqualifying the way it often is elsewhere.

Common Mistakes Growing Companies Make When Financing Equipment

A few patterns show up often enough to be worth flagging before signing anything.

Waiting until cash is already tight to start the financing conversation is one of the most common. Approval and funding take some amount of time even at their fastest, so starting the process before the equipment is needed, not after, avoids a scramble.

Matching the loan or lease term to how long the equipment will actually stay useful is another. A term that runs longer than the equipment’s useful life means paying for something the business has already replaced.

Overlooking soft costs is a third. Delivery, installation, and ongoing maintenance are often left out of a budget built around the sticker price of the equipment alone, when in most cases those costs can be rolled into the financing itself instead of paid separately out of pocket.

Financing Commercial Equipment with Dimension Funding

Dimension Funding has financed equipment for small and mid-sized businesses since 1978, working with almost any equipment vendor a company chooses rather than a fixed list of approved suppliers.

Approvals up to $250,000 are available without financial statements, and most decisions come back quickly, with funding often available within 48 hours of approval. Terms extend up to 60 months, and both loan and lease structures are available depending on which fits a company’s tax and balance sheet goals better. Financing over $250,000 requires financial statements but still moves through a streamlined process rather than a traditional bank underwriting timeline.

Delivery, installation, and maintenance costs can be rolled into the financed amount, and the application itself is a short electronic form rather than a stack of paperwork, with most agreements signed and finalized without a single trip to a bank branch.

Equipment vendors who want to offer financing directly to their own customers can also look into Dimension Funding’s vendor partner programs, which let a sales team answer the payment question on the spot instead of losing a deal to a slow financing decision.

Frequently Asked Questions About Financing Commercial Equipment

Is it better to finance or lease commercial equipment?

It depends on the goal. Financing builds equity toward ownership from day one, while a lease, depending on how it is structured, can either mirror ownership for tax purposes or keep the equipment off the balance sheet. An accountant can weigh in on which fits a specific company’s situation.

How much financing is available without financial statements?

Approvals up to $250,000 don’t require financial statements. Financing above that amount requires financials but still moves through a streamlined process rather than a traditional bank underwriting timeline.

How fast can commercial equipment financing get approved?

Approvals often come back within 24 hours, and funding is commonly available within 48 hours of approval, much faster than the multi-week process typical of a traditional bank loan.

Can financed equipment still qualify for the Section 179 tax deduction?

In many cases, yes. Financing a purchase does not disqualify it from Section 179 treatment, so a business can often keep its cash on hand and still take the deduction in the year the equipment is placed in service. The specifics depend on the company’s tax situation, so this is worth confirming with an accountant.

Does a company need strong credit to finance commercial equipment?

Not necessarily. Approval tends to weigh the overall picture, time in business, revenue trends, and how the equipment supports the company’s plans, rather than a single credit score cutoff, so credit profiles from strong to marginal are commonly considered.

What does Dimension Funding’s commercial equipment financing include?

Delivery, installation, and maintenance costs can be rolled into the financed amount, and equipment can come from almost any vendor a business chooses rather than a fixed list of approved suppliers.

If growth is being held back by equipment a company cannot justify paying cash for, use the payment calculator to see what a monthly payment could look like, or start a financing application to get a quote, usually within a few hours.

Automated Material Handling: Equipment Types & Implementation Costs

automated material handling

Automated Material Handling: Equipment Types & Implementation Costs

A plant manager watches the same pallet get touched by four different people between the production line and the truck, each handoff adding time, a chance for damage, and a chance for someone to get hurt lifting something they should not be lifting by hand. 

Automated material handling cuts that kind of repetitive handling out of the process, whether it runs inside a manufacturing plant, a distribution center, or both.

What Is Automated Material Handling?

Automated material handling covers the equipment and systems that move, store, and control the flow of goods without a person doing the physical work at each step. That includes everything from a conveyor line running product between two machines to a fully automated storage system that stores and retrieves pallets on its own.

Most facilities do not automate everything at once. A common starting point is automating the single biggest bottleneck, whether that is a manual palletizing station, a storage area that has run out of usable space, or a transport route that ties up too much labor, then expanding from there once the first piece proves itself out.

Types of Automated Material Handling Equipment

Conveyors

Belt, roller, and overhead conveyors move product continuously between stations without anyone carrying it by hand. They form the backbone of most automated lines, connecting other equipment like palletizers, sortation systems, and packaging machines into a single continuous flow.

Automated Storage and Retrieval Systems (AS/RS)

AS/RS use cranes, shuttles, or vertical lift modules to store and retrieve palletized or unit-level inventory inside dense racking, bringing product to a person or a downstream process instead of sending a person into the racks to get it.

Automated Guided Vehicles and Autonomous Mobile Robots

AGVs follow a fixed route to move pallets, carts, or totes between two points, while AMRs use sensors and mapping software to navigate more freely and reroute around obstacles. Both replace the manual forklift or cart trips that eat up labor hours on repetitive transport.

Robotic Palletizers and Depalletizers

These systems stack cases, bags, or totes onto a pallet, or break a loaded pallet back down, using robotic arms fitted with vacuum, clamp, or fork-style end effectors depending on what is being handled. Palletizing is repetitive and physically hard on a person’s back, which makes it one of the more common starting points for automation.

Sortation Systems

Sortation equipment routes items to the correct destination, whether that is a shipping lane, a production cell, or a specific order, using diverters, tilt trays, or cross-belt mechanisms tied to a barcode or RFID read.

Carousels and Vertical Lift Modules

Horizontal carousels and vertical lift modules rotate shelves or trays to bring stored items directly to an operator, cutting down on the walking and searching that eats up time in a manual picking operation.

Robotic Piece Picking

Robotic arms equipped with vision systems and grippers can identify and pick individual items out of a bin, a task that historically required a person standing at that station for an entire shift.

How Automated Material Handling Gets Implemented

Implementation is a process, not a delivery date, and it usually runs through the same general phases regardless of which equipment is involved.

It starts with an assessment of current material flow, cycle times, and facility constraints, since the right equipment depends entirely on what is actually moving through the building and how. From there, engineers design the system layout and the control architecture that will run it, followed by procurement and installation of the physical equipment itself.

Integration is where the automation gets connected to a warehouse management system, a manufacturing execution system, or an ERP, so the equipment knows what to do and when. Testing, often done in stages at the vendor’s facility and again once the equipment is on-site, confirms everything works before it touches live production.

The last phase, ramp-up, is easy to underestimate. Employees are still learning the system, throughput builds gradually rather than hitting full speed on day one, and it takes real operating time before a new automated process runs as smoothly as the manual one it replaced. A payback estimate that skips this adjustment period and assumes instant results is usually the first number that turns out to be wrong.

Signs a Process Is Ready to Automate

Not every manual task needs a robot. A few patterns tend to show up in the processes that actually pay off once automated.

The clearest candidates are repetitive and predictable, the same motion or route run hundreds of times a day with little variation, and physical enough to drive injuries, workers’ compensation claims, or turnover, palletizing and repetitive lifting being classic examples. 

A role nobody can keep staffed no matter what it pays is another strong signal, and so is a single station that bottlenecks everything downstream regardless of how well the rest of the line runs.

A process that changes constantly, handles highly irregular product, or runs at low enough volume that the payback period stretches for years is usually a poor first candidate. Starting with the clearest bottleneck, rather than the most impressive piece of equipment, tends to produce the better outcome.

What Drives Implementation Costs

The equipment itself is usually not the biggest surprise in a material handling automation budget. A few other cost drivers tend to catch businesses off guard.

Integration software and controls, the layer that connects new equipment to an existing WMS, MES, or ERP, can cost as much as the physical hardware depending on how custom the connection needs to be. Facility modifications, things like reinforced flooring for a heavy AS/RS installation, added power capacity, or building changes to fit a new conveyor line, are often underestimated when a project is first budgeted.

Training and change management matter too. Staff need to learn new workflows, and a facility usually needs updated safety procedures once people are working alongside automated equipment rather than doing the task themselves. Ongoing maintenance and support, whether handled in-house or through a service contract, is a real recurring cost rather than a one-time line item.

Taken together, these costs are frequently a large share of total project spend, not a minor addition to the price of the machinery.

Financing Your Automated Material Handling Project with Dimension Funding

Dimension Funding has financed industrial equipment and technology for over 40 years, and both industrial automation financing and material handling equipment financing are set up to cover a multi-phase project like the one described above, not just a single piece of equipment.

Instead of funding a project in pieces out of different budgets, financing rolls the entire scope, equipment, integration, installation, and training, into one fixed monthly payment. 

Approvals up to $500,000 are available without financial statements, and credit approvals for larger automation projects range from $25,000 up to $25,000,000. Terms extend up to 60 months, with no penalty for paying off the balance early.

The software and controls layer that connects new equipment to existing systems can be financed too, alongside the physical equipment, through Dimension Funding’s IT and technology financing. That matters given how much of an automation budget lives in integration rather than steel and motors.

Businesses financing this kind of project may also be able to write off a significant portion of the cost under IRS Section 179 in the same tax year the equipment goes into service, which can offset a meaningful part of the investment before the first full year of operation wraps up.

Automation integrators and equipment manufacturers who want to offer financing directly to their own clients can look into Dimension Funding’s vendor partner programs, which give a sales team a way to answer the budget question on the spot instead of waiting on a customer’s internal approval process.

Frequently Asked Questions About Automated Material Handling

What is automated material handling?

Equipment and systems, conveyors, AS/RS, AGVs and AMRs, robotic palletizers, sortation, that move, store, and control the flow of goods without a person doing the physical work at each step.

What equipment counts as automated material handling?

Conveyors, automated storage and retrieval systems, automated guided vehicles and autonomous mobile robots, robotic palletizers and depalletizers, sortation systems, carousels and vertical lift modules, and robotic piece-picking arms are the main categories.

How much does it cost to implement?

It depends on scope, but the equipment itself is rarely the biggest surprise. Integration software, facility modifications like reinforced flooring or added power, training, and ongoing maintenance often make up a large share of the total.

How long does implementation take?

It varies by project. A single piece of equipment added to an existing line moves faster than a project that spans assessment, design, procurement, integration, and a multi-week ramp-up before it reaches full production volume.

Can automated material handling be financed?

Yes. Dimension Funding finances the equipment, integration software, installation, and training involved in a project as one fixed monthly payment instead of requiring the full cost upfront.

How long does approval take?

Approvals up to $500,000 don’t require financial statements, and most credit decisions come back within a few hours. Larger projects, up to $25,000,000, involve more documentation but are handled by the same team from quote to funding.

If a manual process is costing more in labor, damage, or injuries than it should, use the payment calculator to see what a monthly payment could look like, or start a financing application to get a quote, usually within a few hours.

Pallet Racking Systems: 9 Types Compared + Installation & Financing

pallet racking

Pallet Racking Systems: 9 Types Compared + Installation & Financing

A warehouse manager signs off on a new racking layout, waits weeks for it to arrive and get installed, and only then realizes the forklifts on the floor cannot reach the second row. That single mismatch between rack type and equipment can turn a storage upgrade into a redo, with the whole project sitting idle while someone figures out what went wrong. Picking the right pallet racking system before anything gets ordered is the difference between the two.

What Is Pallet Racking?

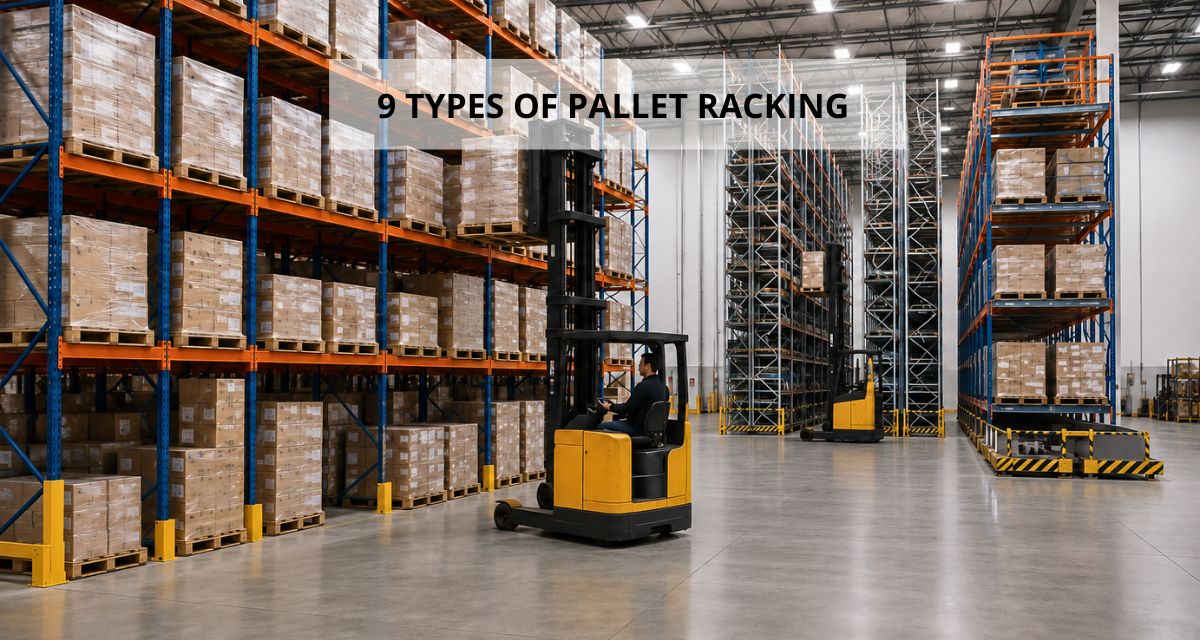
Pallet racking is a structural storage system built from vertical frames and horizontal beams that holds palletized inventory above the floor, usually several levels high. Instead of stacking pallets directly on top of each other, racking lets a forklift place and retrieve pallets at defined levels. 

That protects the product underneath, puts vertical space to use that would otherwise sit empty, and keeps inventory organized enough to actually find when someone needs it.

Not every rack type solves the same problem. Some prioritize getting to every pallet whenever you need it. Others sacrifice that access in exchange for packing far more product into the same floor space.

9 Types of Pallet Racking Systems Compared

1. Selective Racking

The standard rack type in most warehouses. Every pallet sits directly accessible from the aisle, works with any standard forklift, and supports any inventory rotation method. It uses floor space less efficiently than denser systems, but the tradeoff is that any pallet can be pulled at any time without moving another pallet first.

2. Double-Deep Racking

Pallets store two positions deep instead of one, so more inventory fits in the same footprint. The catch is that a standard forklift cannot reach the back pallet. Double-deep requires a truck with telescoping or reach forks built for the second row.

3. Drive-In Racking

Forklifts drive directly into the rack structure itself to load and unload pallets, with only one aisle serving as both entry and exit. This packs pallets tightly but locks the system into last-in, first-out rotation, since the first pallet loaded ends up buried behind everything that came after it.

4. Drive-Through Racking

Structurally similar to drive-in, but open on both ends so a forklift can enter from one side and exit the other. That opens up first-in, first-out rotation, useful for perishable goods or anything with a shelf life.

5. Push-Back Racking

Pallets sit on wheeled carts on a slightly sloped rail system. A forklift pushes each new pallet back, and gravity feeds the next pallet forward when one is removed. Push-back typically stores pallets two to six deep per lane and still allows access from a single aisle.

6. Pallet Flow Racking

Also called gravity flow, this system uses angled roller tracks so pallets loaded at the high end roll down to the pick end under their own weight. Loading and picking happen from opposite ends of the same lane, so it supports true first-in, first-out rotation at high density.

7. Cantilever Racking

Built with arms extending from a single vertical column instead of enclosed bays, cantilever racking is designed for long or awkward loads that do not sit well on a standard pallet, things like lumber, pipe, or metal bar stock.

8. Very Narrow Aisle (VNA) Racking

Standard selective racking built for aisles far tighter than a conventional forklift can turn in, paired with specialized VNA trucks that move on guide rails or wire guidance. The narrower aisles reclaim floor space that would otherwise sit empty for truck turning radius.

9. Mobile Racking

Rack rows sit on motorized carriages that roll along floor-mounted rails, closing the aisle between rows until someone needs access. Only one aisle needs to be open at any given time, so a warehouse can fit meaningfully more racking into the same building footprint.

How to Choose the Right System

The decision usually comes down to a handful of practical questions rather than a single best answer. 

What forklifts are already on the floor, and can they reach a double-deep or VNA layout without buying new trucks? Does inventory need strict first-in, first-out rotation, which rules out drive-in racking, or is last-in, first-out acceptable for the product being stored? How much of the building’s footprint needs to go toward storage versus staging, receiving, and aisle space for daily operations?

Ceiling height and building growth plans matter too. A warehouse expecting to add SKUs or scale volume in the next few years benefits from a system that is not maxed out on day one. Getting this wrong is expensive to fix later, since it usually means tearing out and replacing a system rather than adjusting it.

Common Mistakes When Planning a Racking Layout

A few mistakes show up often enough to be predictable, and most of them are avoidable with a bit of planning before steel gets ordered.

Ordering racking before confirming which forklifts will actually service it is the most common one, and it is the exact scenario from the opening of this piece. A double-deep or VNA layout does nothing for a warehouse if the trucks already on the floor cannot reach it.

Sizing a layout for today’s inventory instead of where the business expects to be in two or three years is another. Racking is expensive to tear out and replace, so building in some headroom upfront is usually cheaper than a second project down the line.

Skipping engineered drawings and proper anchoring to save time or money is the costliest mistake by far. It turns a budget decision into a safety problem. A system that is not engineered and anchored to code can fail under load, and the cost of a collapse is far higher than whatever the engineering step would have added to the price.

Pallet Racking Installation Requirements

Racking is a structural system, not furniture, and it is regulated as one. The Rack Manufacturers Institute’s ANSI MH16.1 standard governs how racking is designed, loaded, and anchored, and most reputable installers work directly against it.

Every loaded rack column needs to be anchored to the floor, not just the columns along the aisle. The floor itself needs to be engineered to handle the point loads a fully loaded rack system puts on a relatively small footprint, something most warehouse floors were never built to handle on their own. In earthquake-prone regions, seismic requirements add additional bracing and anchoring specifications on top of the base standard.

Load capacity signage, regular inspections, and a plan for repairing damaged frames (a forklift strike bends steel more often than most warehouses expect) are part of keeping a system compliant long after installation day. Skipping any of this is how a storage upgrade turns into a safety liability instead of a productivity win.

What Does Pallet Racking Cost?

Cost depends on the type of system, the height and depth of the layout, and how much engineering and installation labor the project needs. Selective racking is the least expensive option per pallet position, while systems like mobile racking or VNA cost considerably more upfront, since they require specialized equipment and more precise installation, in exchange for the extra density or space savings they deliver.

Installation, permitting, floor engineering, and any building modifications needed to support the system are usually a significant part of the total project cost, not an afterthought tacked onto the price of the steel itself.

Financing Your Pallet Racking Project with Dimension Funding

Dimension Funding has provided material handling equipment financing for over 40 years, and that coverage extends to warehouse storage racks and shelving directly, not just the forklifts and equipment that move pallets in and out of them.

Rather than paying for a racking project in cash, financing spreads the full cost, including racking, installation, and any related equipment, into one fixed monthly payment. 

Approvals up to $250,000 are available without financial statements, and larger projects go through a streamlined process rather than a traditional loan application. Terms extend up to 60 months, with no penalty for paying off the balance early.

Delivery, installation, and maintenance costs can be included in the financed amount rather than paid upfront out of pocket. That matters, since a meaningful share of a racking project’s total cost sits outside the steel itself.

Businesses financing a racking project may also be able to write off a significant portion of the cost under IRS Section 179 in the same tax year the system is installed, which can meaningfully offset the investment.

Frequently Asked Questions About Pallet Racking

What is the most common type of pallet racking?

Selective racking. It gives direct access to every pallet from the aisle, works with any standard forklift, and fits almost any inventory rotation method, which is why most warehouses start there before considering a denser system.

What is the difference between drive-in and drive-through racking?

Drive-in has one aisle that serves as both entry and exit, so it only supports last-in, first-out rotation. Drive-through is open on both ends, which allows first-in, first-out rotation instead.

How much does pallet racking cost to install?

It depends on the system type and the amount of engineering, permitting, and labor the layout needs. Selective racking is the least expensive per pallet position, while denser systems like mobile racking or VNA cost more upfront because of the specialized equipment and more precise installation involved.

Does pallet racking need to be anchored to the floor?

Yes. Every loaded column needs to be anchored, and the floor itself needs to be engineered to handle the point loads a fully loaded system creates. The Rack Manufacturers Institute’s ANSI MH16.1 standard governs how this is done, and seismic zones require additional bracing on top of that.

Can pallet racking be financed?

Yes. Dimension Funding finances warehouse storage racks and shelving directly, along with installation and related equipment, as one fixed monthly payment instead of a large upfront cost.

How long does approval take?

Approvals up to $250,000 don’t require financial statements, and most decisions come back within a few hours. Larger projects involve more documentation but are still handled by the same team from quote to funding.

If a storage upgrade is on the table, use the payment calculator to see what a monthly payment could look like, or start a financing application to get a quote, usually within a few hours.

Warehouse Automation Financing: Systems, ROI & Financing Options

warehouse automation

Warehouse Automation Financing: Systems, ROI & Financing Options

It is peak season, order volume just spiked well past what the schedule was built for, and the warehouse manager is short four pickers with no applicants in the pipeline. 

Overtime is already maxed out, error rates are climbing, and the shipping deadline does not move. This is the moment most operations stop talking about warehouse automation and actually start pricing it out.

What Is Warehouse Automation?

Warehouse automation means using software and machinery to handle tasks that were previously done by hand, receiving, storing, picking, packing, and shipping. That can mean a full automated storage and retrieval system running around the clock, or something as simple as a warehouse management system that tells staff exactly where to walk and what to grab.

Most operations do not jump straight to a fully automated building. They add automation in layers, usually starting with software, then picking support, then heavier equipment, as volume and budget justify each step.

Types of Warehouse Automation Systems

Different systems solve different bottlenecks. Here is where most warehouses start.

Warehouse management systems (WMS). Software that tracks inventory, assigns tasks, and directs staff or equipment to the right location. A WMS is often the foundation everything else connects to, including warehouse execution and control systems that coordinate robots and conveyors on the floor.

Automated storage and retrieval systems (ASRS). These systems store inventory in dense racking and retrieve it automatically, using shuttles, cranes, or vertical lift modules to bring product to a person instead of sending a person to product.

Conveyor and sortation systems. Conveyors move goods through receiving, picking, packing, and shipping, while sortation systems automatically route items to the correct dock door, chute, or order based on barcode or RFID data.

Pick-to-light and voice picking. Light-directed and voice-directed picking point workers straight to the right bin and quantity, cutting down the time spent searching and double checking an order.

AGVs and AMRs. Automated guided vehicles and autonomous mobile robots move pallets, carts, and totes around the floor without a forklift operator, either along a fixed route or navigating around obstacles on their own.

Robotic piece picking. Robotic arms equipped with vision systems and grippers can pick individual items out of a bin and place them into an order container, a task that used to require a person standing at that station for an entire shift.

Fixed systems like conveyors, sortation lines, and ASRS work best in buildings with a stable layout and predictable volume. They cost more upfront and are harder to reconfigure later, but they handle high, steady throughput extremely well. 

Robots and mobile systems trade some of that raw throughput for flexibility, which matters more in a facility whose layout or order profile changes often.

How to Think About ROI on Warehouse Automation

Every automation vendor has a payback number ready to quote, and most of those numbers come from someone else’s best week, not your building. A more useful approach is to look at the same four categories every automation project affects and estimate them for your own operation.

Labor. Automation reduces the number of people needed for repetitive transport and picking tasks, but it rarely eliminates staff entirely. The real savings usually show up in reduced overtime, lower reliance on temporary labor during peak season, and fewer open positions competing for a shrinking pool of warehouse workers.

Accuracy and returns. Manual picking and packing carry a natural error rate. Systems that direct or verify each pick, such as pick-to-light or barcode scanning tied to a WMS, tend to cut down on mis-ships and the return shipping, restocking, and customer service costs that come with them.

Throughput and space. Automated storage can pack more inventory into the same square footage than open aisles built for forklift access, and consistent equipment speed makes daily output easier to forecast. That matters most for operations paying for warehouse space by the square foot or facing a lease renewal.

Total cost versus total payment. The number that actually matters for a purchase decision is not the sticker price of the equipment. It is whether the monthly financing payment is lower than what the automation replaces in labor, error, and space costs each month. When it is, the project pays for itself from day one instead of after some multi-year break-even point on a spreadsheet.

Any of these estimates should be built with your integrator and finance team using your own order volume, labor costs, and building constraints, not a vendor’s generic case study.

Signs Your Warehouse Is Ready for Automation

A few patterns tend to show up before a warehouse is ready to automate. Order volume has outpaced the ability to hire and train new staff, and the same pallet or tote routes get run so often that a fixed path could handle them without anyone walking the floor. 

Peak season leans hard on overtime and temp labor just to hit shipping deadlines, and picking or packing errors are common enough to show up in customer complaints or return rates.

If none of that sounds familiar yet, automation may still be premature. A warehouse with constantly shifting layouts, low and unpredictable volume, or highly irregular one-off orders often gets more value from process changes or a lighter WMS upgrade before committing to heavier equipment.

What Does Warehouse Automation Cost?

Cost depends entirely on scope. A WMS or picking software rollout costs far less than a conveyor and sortation system, and a full ASRS installation with racking, shuttles, and integration is a much larger project than a handful of AGVs added to an existing floor plan.

Beyond the equipment itself, most projects include software licensing, installation, integration with existing systems, staff training, and ongoing maintenance and support. Those costs add up fast, and they are often underestimated when a business budgets only for the hardware.

Timeline matters too. A WMS rollout can go live in a matter of weeks, while a conveyor and sortation system tied into building construction or a facility expansion can take months of planning before the first pallet ever moves through it. Financing terms should account for that gap between when the payments start and when the system is fully operational and delivering savings.

That combined price tag is usually the reason automation projects stall at the budget approval stage, even when the operational case is clear. Financing closes that gap.

Financing Your Warehouse Automation Project with Dimension Funding

Dimension Funding has financed industrial and material handling equipment for over 40 years, working with manufacturers and distributors who need to modernize a facility without tying up cash reserves. Both industrial automation financing and material handling equipment financing cover this kind of project directly.

Instead of paying for a warehouse automation rollout in cash, financing turns the entire project into one fixed monthly payment. Approvals up to $500,000 are available without financial statements, and credit approvals for larger automation projects run from $25,000 up to $25,000,000. Terms extend up to 60 months, with no penalty for paying off the balance early.

The financing is not limited to the physical equipment. Software licensing for a WMS or execution system, IT and technology costs, integration, staff training, and ongoing maintenance can all be rolled into the same payment, so a project is not funded piecemeal out of different budgets.

Businesses financing this kind of equipment may also be able to write off a meaningful portion of the cost under IRS Section 179 in the same tax year the system goes live, which can offset part of the investment before the first full year of operation is even finished.

Automation integrators, WMS vendors, and equipment manufacturers who want to offer financing directly to their own clients can look into Dimension Funding’s vendor partner programs, which give sales teams a way to answer the budget objection on the spot instead of losing momentum waiting on a customer’s finance department.

Frequently Asked Questions About Warehouse Automation

What is warehouse automation?

It means using software and equipment, a WMS, conveyors, ASRS, AGVs, robotic picking, to handle receiving, storage, picking, and shipping tasks that used to be done by hand.

What is the ROI of warehouse automation?

It depends on your labor costs, order volume, and building constraints, so there is no single number that applies to every warehouse. The categories worth measuring are labor, accuracy, throughput and space, and whether the financing payment is lower than what automation replaces each month.

How much does warehouse automation cost?

It ranges widely. A WMS or picking software rollout costs far less than a conveyor and sortation system, and a full ASRS installation is a bigger project than adding a handful of AGVs to an existing floor. Software licensing, integration, training, and maintenance are usually part of the total, not just the hardware.

Can warehouse automation be financed?

Yes. Dimension Funding finances the equipment, software, integration, training, and maintenance involved in a warehouse automation project as one fixed monthly payment, rather than requiring the full cost upfront.

What does Dimension Funding’s warehouse automation financing cover?

WMS or execution system software, physical equipment such as conveyors, ASRS, or AGVs, integration and installation, staff training, and ongoing maintenance, all rolled into a single payment.

How long does approval take?

Approvals up to $500,000 don’t require financial statements, and most credit decisions come back within a few hours. Larger automation projects, up to $25,000,000, involve more documentation but are handled by the same team from quote to funding.

If overtime, error rates, or missed shipping deadlines are becoming a pattern rather than a one-off, use the payment calculator to see what a monthly payment would look like for your project, or start a financing application to get a quote, usually within a few hours.

What Is an AGV? Automated Guided Vehicles Explained + Financing

AGV

What Is an AGV? Automated Guided Vehicles Explained + Financing

A warehouse manager watches the same forklift operator make the same trip across the floor for the tenth time that hour, carrying a pallet from receiving to a storage rack forty feet away. Multiply that trip by every shift, every day, and the labor cost adds up fast, especially when open forklift positions sit unfilled for weeks. That repetitive trip is exactly what an AGV replaces.

What Is an AGV (Automated Guided Vehicle)?

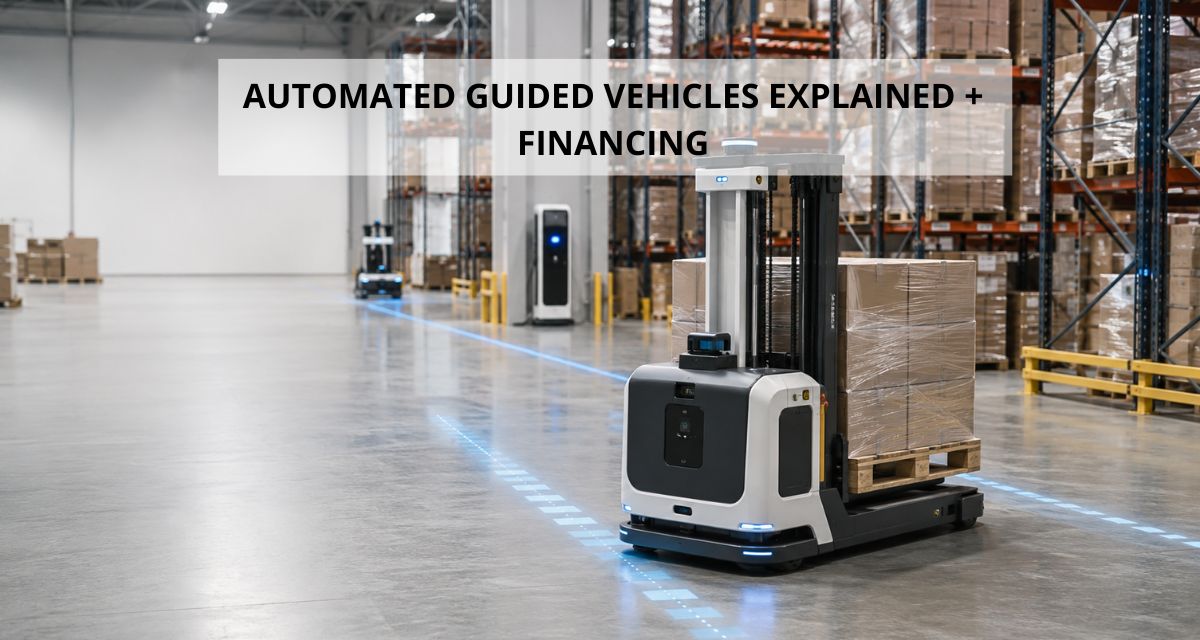
An AGV, short for automated guided vehicle, is a self-driving vehicle that moves materials through a warehouse, distribution center, or manufacturing plant without a human driver. It follows a set path between two points, picks up a load, and delivers it the same way, every time.

AGVs are not a new idea. Manufacturers and distributors have used them for decades to move pallets, carts, and raw materials along fixed routes. What has changed is the range of AGV types now available and how affordable the technology has become for mid-sized operations, not just large enterprise plants.

How Do AGVs Work?

An AGV reads its environment through a guidance system, follows a pre-mapped route, and communicates with a warehouse management system or fleet controller that assigns it tasks. When a pallet needs to move from dock door 3 to rack aisle 12, the system dispatches the nearest available AGV, which then navigates the route, picks up the load, and drops it at the destination.

Guidance and Navigation Methods

Most AGVs rely on one of a few navigation approaches. Magnetic tape or embedded floor wires guide the vehicle along a fixed track. Laser targets placed around the facility let the AGV triangulate its position. 

QR code markers on the floor give the vehicle fixed reference points. Some newer AGVs use vision systems or LiDAR to read the surrounding environment while still operating along a defined route.

AGVs run on rechargeable batteries, usually lithium-ion or lead-acid, and most fleet management software automatically routes a vehicle to a charging station once its battery runs low, so operations rarely need to stop for charging.

Types of Automated Guided Vehicles

Not every AGV looks or works the same. The right type depends on what is being moved and how far it needs to travel.

Forklift AGVs handle pallets the same way a traditional forklift does, lifting and placing loads on racks, but without an operator in the seat.

Tow or tugger AGVs pull a line of carts behind them, similar to a small train, which makes them efficient for moving several loads across long distances in one trip.

Unit load AGVs carry a single load, such as a pallet or a bin, on a flat deck or conveyor top, and are common in manufacturing lines that feed parts to a workstation.

Automated guided carts (AGCs) are the simplest and most affordable AGV type, often used for sorting, cross-docking, or moving smaller items around a facility.

Heavy burden carriers are built for oversized or overweight loads, such as coils, rolls, or large industrial components, and are common in steel, paper, and heavy manufacturing.

AGV vs AMR: What Is the Difference?

AGV and AMR (autonomous mobile robot) get used interchangeably, but they are not the same thing. An AGV follows a fixed path set by tape, wire, or laser targets, and it needs a human to clear the way if something blocks its route. 

An AMR uses sensors and mapping software to build its own understanding of the facility and can reroute itself around an obstacle without stopping the whole operation.

AGVs tend to fit facilities with a stable, repeatable layout where the same route is run thousands of times a day. AMRs make more sense when a facility’s layout changes often or when flexibility matters more than raw throughput. Many operations end up running both, using AGVs for high volume repetitive routes and AMRs for tasks that need more adaptability.

Benefits of Adding AGVs to Your Operation

The case for AGVs usually comes down to a handful of practical changes that show up on the floor within the first few months.

Lower labor costs. Fewer people are tied up running repetitive material transport, so the staff who remain can focus on work that actually needs a person, like quality control or order accuracy.

Fewer errors. An AGV runs the same route the same way every time, so the product damage and misplaced inventory that come with manual handling tend to drop off.

Fewer safety incidents. Cutting down on forklift trips through pedestrian areas removes one of the more common causes of warehouse accidents.

More predictable output. An AGV does not take breaks, slow down near the end of a shift, or need retraining when someone new is hired, which keeps throughput steadier during peak season.

Industries That Use AGVs

AGVs show up well beyond automotive plants these days. Manufacturers rely on them to feed parts to assembly lines and move finished goods to shipping. Distribution centers and 3PLs use them to shuttle pallets between receiving, storage, and staging. 

Food and beverage facilities run them through cold storage without adding staff to a tough environment. Pharmaceutical and medical manufacturers lean on them because a fixed, documented route holds up better under compliance review than a manual one.

Signs Your Operation Is Ready for AGVs

AGVs work best in facilities with a layout that does not change every few weeks and routes that repeat often enough to justify the investment. A few signals point to a good fit.

The same pallet path gets run dozens or hundreds of times a shift. Forklift operator positions sit open for weeks at a time, and existing staff are stretched thin covering routine transport. Damage claims or near miss incidents keep showing up in the same aisles, which points to a human error problem more than an equipment problem.

A facility that reconfigures its layout constantly, or handles mostly irregular loads, will likely get more value from AMRs or a mix of both vehicle types. A quick walkthrough with an automation integrator usually settles which approach fits before any money changes hands.

What Does an AGV Cost?

AGV pricing depends heavily on the type of vehicle, the number of units in a fleet, and how much site work is needed for navigation infrastructure, software integration, and staff training. 

A single forklift AGV costs more than a traditional forklift, and a full fleet with fleet management software, charging infrastructure, and integrator support represents a significant capital project for most mid-sized businesses.

That upfront cost is usually the biggest obstacle standing between a warehouse manager who wants AGVs and a finance team that has to approve the purchase. This is exactly where financing changes the math.

Financing Your AGV Investment with Dimension Funding

Dimension Funding has provided industrial automation financing and material handling equipment financing for over 40 years, working with manufacturers and distributors who need to add robotics and automation without draining working capital.

Rather than paying for an AGV project in cash, financing spreads the cost of the vehicles, software, installation, training, and multiple years of support into one fixed monthly payment. 

Approvals up to $500,000 are available without financial statements, and credit approvals range from $25,000 up to $25,000,000 for larger automation projects. Terms extend up to 60 months, and there are no prepayment penalties if a business wants to pay off the balance early.

Financing can also cover the full project cost, not just the vehicles themselves. Design, implementation, consulting, training, and maintenance can all be rolled into the same fixed payment, so a business is not stuck paying separately for the parts of an AGV rollout that make it actually work on day one.

Businesses that finance equipment purchases may also be able to write off a significant portion of the cost under IRS Section 179, which can offset a meaningful part of the investment in the same tax year the AGVs go into service.

AGV manufacturers, integrators, and dealers looking to offer financing to their own clients can also explore Dimension Funding’s vendor partner programs, which help close deals faster by removing the “how do we pay for this” objection from the sales conversation.

Frequently Asked Questions About AGVs

What is an AGV used for?

Moving materials, pallets, carts, bins, or raw stock, between fixed points on a floor. It’s the job that would otherwise tie up a forklift operator for an entire shift.

What’s the difference between an AGV and an AMR?

An AGV follows a set path (tape, wire, or laser targets) and needs a clear route to keep moving. An AMR reads its surroundings and reroutes itself around obstacles without anyone stepping in.

How much does an AGV cost?

It varies by vehicle type, fleet size, and how much site work the integration needs. A single unit runs more than a standard forklift, and a full fleet with fleet management software and charging infrastructure is enough of an investment that most businesses finance it instead of paying cash upfront.

Can AGVs be financed?

Yes. Dimension Funding finances AGVs and other industrial automation equipment, along with the software, installation, training, and support that come with them, as one fixed monthly payment.

What does AGV financing from Dimension Funding cover?

The vehicles themselves, plus design, implementation, consulting, training, and multiple years of maintenance and support, all rolled into a single payment instead of billed separately as the project moves along.

How long does approval take?

Approvals up to $500,000 don’t require financial statements, and most credit decisions come back within a few hours. Larger automation projects, up to $25,000,000, involve more paperwork but are still handled by the same team from quote to funding.

If your operation is ready to move materials with fewer people, fewer errors, and less downtime, use the payment calculator to see what a monthly payment could look like, or start a financing application to get a quote, usually within a few hours.

CNC Machine Vendor Financing: Loans for Mills, Lathes & Automation

cnc machine financing

CNC Machine Vendor Financing: Loans for Mills, Lathes & Automation

A shop owner walks your showroom floor, likes the five axis mill, likes the quote, and then goes quiet the moment the total comes up. 

That pause is the moment a lot of machine tool sales are won or lost. The equipment is right, the price is fair, and the deal still stalls because the buyer has no easy way to pay for it without tying up capital they need for payroll, materials, and the next job.

CNC machine vendor financing exists to remove that pause. Instead of sending a customer off to shop banks on their own, a mill or lathe dealer can offer financing at the point of sale, get paid in full once the machine ships, and let the customer pay it off in one predictable monthly payment.

Why CNC Machine Buyers Hesitate at the Quote

Machine tools are not a small purchase. A CNC machining center commonly runs anywhere from $50,000 to $500,000 depending on size and configuration, vertical machining centers often land between $75,000 and $300,000, and CNC lathes and turning centers typically fall somewhere between $50,000 and $300,000. Add tooling, controls, installation, and rigging, and the real number a buyer has to plan for climbs well past the machine’s base price.

That kind of ticket size is exactly why cash flow becomes the deciding factor. A shop can want the machine and still walk away if paying cash means draining the working capital it needs to keep running jobs. Financing turns that same purchase into a monthly payment that fits inside the shop’s existing budget instead of disrupting it.

What Offering Financing Does for a Machine Tool Dealer

Financing is not just a convenience for the buyer, it changes the outcome of the sale. Forrester Research found that vendors offering point of sale financing increased their sales by an average of 32 percent, and machine tool dealers see the same dynamic play out on the shop floor. 

A customer who was ready to walk because of the price tag often stays in the conversation once financing is on the table.

Offering financing also changes how a dealer gets paid. Instead of waiting on a buyer to arrange their own loan, a dealer working with a financing partner gets paid in full once the transaction closes, while the customer makes payments to the finance company over time. That removes the collection risk from the dealer entirely and speeds up how quickly a closed deal turns into cash in the business.

Loan or Lease: How CNC Financing Gets Structured

Buyers generally have two paths once they decide to finance the purchase.

A loan puts ownership of the machine on the buyer’s books from day one. It suits a shop that plans to run the equipment for its full working life, often seven to ten years for a well maintained CNC machine, and that wants the depreciation benefit that comes with owning the asset outright.

A lease usually carries a lower monthly payment and gives the shop more flexibility. At the end of the term, the buyer can purchase the machine, return it, or move up to newer equipment, which appeals to shops that expect their production needs or technology requirements to change before the machine wears out.

Terms for CNC and industrial equipment financing commonly run from 24 to 72 months, with 60 months being a common standard for new machines. The right structure depends on how long the buyer expects to keep the equipment and how they want the asset to show up on their books.

Financing Automation Cells Alongside the Machine

A CNC purchase increasingly comes with more than the machine itself. Robotic loading and unloading, vision systems, conveyors, and the software that ties a cell together all add cost on top of the mill or lathe, and a shop automating a process for the first time often needs design, programming, and training just to get the cell running.

Financing that only covers the machine leaves all of that as a separate expense the buyer has to find cash for elsewhere. 

A program built for industrial automation can instead roll the robotics, integration, programming, and multiple years of support and maintenance into the same agreement as the machine, so the shop ends up paying for one working cell instead of a stack of separately invoiced pieces.

What Buyers Should Have Ready

Preparation affects both approval speed and the terms a buyer gets offered. A down payment somewhere in the 10 to 20 percent range is common across CNC financing generally, and a credit score in the mid 600s or better tends to open up the most competitive terms available.

Speed depends on preparation too. A shop that comes in with a firm equipment quote, the intended use for the machine, and financial statements ready if the amount requires them typically sees a decision within a day or two. Incomplete applications, or ones missing a firm quote from the dealer, take longer regardless of how strong the buyer’s credit is.

Choosing the Right Financing Partner

Not every financing program is built for equipment at this price point and complexity.

Confirm whether the program can finance the whole project, not just the machine itself. Tooling, controls, software, rigging, and installation all cost money, and a financing partner that only covers the base machine leaves the buyer paying for the rest out of pocket. 

Ask how quickly the program pays the dealer, since getting paid at time of shipment rather than waiting on installation or customer approval changes how the deal affects cash flow. And check whether approval requires full financial statements at every dollar amount, since a program that can approve without them up to a meaningful threshold moves faster for both the dealer and the buyer.

How Dimension Funding Structures CNC and Industrial Automation Financing

Dimension Funding finances industrial automation and equipment including CNC mills, lathes, and automated production equipment, with approvals available from $25,000 up to $25,000,000 and up to $500,000 in financing without requiring financial statements. The financing can cover the entire project, equipment, software, and implementation, rather than just the machine on its own.

Dealers who become a vendor partner get paid through 100 percent prefunding before install, so cash comes in before the machine is even installed. Rates are fixed for the entire finance term, there are no prepayment penalties for the customer, and credit turnaround is typically measured in hours rather than days. Buyers can also structure the purchase as an equipment lease instead of a loan, with terms from 12 to 60 months depending on what fits their operation.

Some dealers choose to offer 0 percent financing to their customers, building the cost into pricing so interest rate shopping never becomes part of the sales conversation. Most CNC and automation equipment purchases also qualify for a Section 179 write off, which is worth mentioning to buyers since it can meaningfully lower what the machine costs in its first year.

Buying the Machine Directly

If you’re a shop owner or manufacturer financing a CNC purchase directly rather than through your dealer’s program, the same options apply. You can apply directly for financing on new or used equipment, use a payment calculator to see what a given amount looks like as a monthly payment, and structure the deal as a loan or a lease depending on how long you plan to run the machine.

Frequently Asked Questions

Does CNC machine financing cover tooling and installation, or just the machine?

A well structured program covers the whole project rather than the base machine alone. That can include tooling, controls, rigging, installation, and even robotics or automation tied to the same purchase, all rolled into one agreement instead of separate invoices.

Should a shop finance a CNC machine with a loan or a lease?

It depends on how long the shop plans to keep the machine. A loan builds ownership from day one and suits equipment that will run for its full working life, often seven to ten years. A lease usually carries a lower monthly payment and gives the shop the option to upgrade, return, or buy the machine once the term ends.

How fast do dealers get paid when they offer financing to customers?

Through a vendor financing program, a dealer typically gets paid in full once the transaction closes, sometimes through 100 percent prefunding before the machine is even installed, rather than waiting on the buyer to arrange financing or make payments over time.

Can a machine tool dealer offer 0 percent financing to customers?

Yes. Some dealers build the cost of financing into their pricing so they can offer 0 percent to the buyer. It takes the interest rate out of the sales conversation entirely and keeps the focus on the equipment itself.

What credit score or down payment does a buyer need for CNC financing?

There’s no single number that applies everywhere, but a down payment in the 10 to 20 percent range is common, and a credit score in the mid 600s or better tends to unlock the most competitive terms. Coming to the table with a firm equipment quote also speeds up approval regardless of credit profile.

Can automation and robotic cells be financed along with the CNC machine?

Yes. Robotics, vision systems, conveyors, and the programming or training needed to get a cell running can typically be financed alongside the machine itself, rather than treated as a separate cash expense.

Become a Vendor Partner

Losing a sale because a buyer couldn’t figure out financing on their own is avoidable. Dimension Funding has been financing equipment and software for vendors and their customers since 1978, with a team where much of the sales staff has been in place for over twenty years.

If you sell CNC mills, lathes, or automation equipment and want to offer your customers financing that closes deals instead of stalling them, become a vendor partner or call 1.800.755.0585 to talk it through with a financing expert.

EMR Financing: Streamlining Transitions & Clinical Operations Management

emr financing

EMR Financing: Streamlining Transitions & Clinical Operations Management

Every practice that has switched electronic medical records systems knows the software price quoted at the start of the sales call is never the whole number. 

By the time training, data migration, hardware, and implementation support get added in, the real cost of the transition can be two or three times what the license alone suggested. 

That gap is where a lot of practices get stuck, caught between an outdated system that’s slowing down clinical work and a new one that looks unaffordable once every line item is added up.

EMR financing exists to close that gap. Instead of paying for the software, the implementation team, the training hours, and the new hardware as separate cash expenses, a practice can roll all of it into one predictable monthly payment and keep the transition moving without draining working capital.

Why EMR Transitions Cost More Than the Software Price Tag

Cloud based EMR software is typically billed as a monthly subscription per provider, but that number is rarely the full picture. 

Implementation for a small practice commonly falls somewhere between $20,000 and $65,000 once data migration, configuration, and go live support are added in, and mid-sized clinics often see that range climb to $65,000 or more depending on how many records and workflows have to move over. 

Layer the ongoing subscription on top, often $200 to $700 per provider per month for a cloud based platform, and the first year of a transition can run well past what the initial quote suggested.

Training adds another cost most budgets underestimate. Staff and clinicians need guided practice with the new system before they can use it confidently during patient visits, and that training tends to continue in smaller doses as the system gets updated. Data migration is its own project too, since old records have to be converted and checked for accuracy rather than simply copied over.

Most practices also need updated hardware, tablets for exam rooms, new workstations at the front desk, or servers to support the system depending on how it’s deployed. None of this shows up on the software vendor’s price sheet, which is exactly why so many transitions end up costing more than the practice budgeted for.

How Long an EMR Transition Actually Takes

A full implementation, from contract signing to a staff that’s comfortable using the system with patients, typically takes anywhere from three months to a year depending on the size of the practice and how much data has to migrate from the old system. Rushing that timeline to save money on training usually costs more later in staff errors and support calls than it saves up front.

Most practices see a positive return within twelve to twenty four months once the system is fully adopted, through fewer billing errors, faster documentation, and less time spent chasing down paper records. That return depends heavily on adoption, which is why the training and support portion of a transition is worth financing right along with the software, rather than cutting it to save money up front.

What EMR Financing Covers

A well structured EMR financing arrangement is not just a loan against the software license. It’s built to cover the entire project, which typically includes the EMR or EHR software itself, implementation and configuration services, staff training, data migration, and any hardware needed to run the system, from tablets to servers.

Third party vendors involved in the rollout, such as implementation consultants or data conversion specialists, can usually be included as well. Bundling all of it into a single financing agreement means one monthly payment covers the whole project instead of a scattered set of invoices landing at different times.

How Financing Protects Clinical Operations During the Transition

An EMR transition already disrupts clinical workflow for a period of weeks or months while staff learn the new system. Paying for the entire project in cash on top of that disruption puts real pressure on a practice’s working capital right when it needs flexibility most.

Financing spreads the cost over a term that matches how long the practice expects to use the system, rather than requiring the full amount up front. 

That keeps cash available for payroll, supplies, and the normal cost of running a practice while the new EMR system is still being adopted. It also makes the total cost predictable, since the payment does not change even if the transition takes longer than expected.

What to Look for in an EMR Financing Program

Not every financing option covers the same scope.

Confirm whether implementation, training, and data migration are included, or if the financing only covers the software license itself. Check that the program works with the vendor you’ve already chosen, rather than restricting you to a preselected list. 

Find out if approval requires full financial statements or can be handled through a simpler application, since that affects how quickly you can move once you’ve settled on a system. Match the term length to how long you expect to keep the system too, so the payment schedule lines up with its useful life instead of running longer or shorter than makes sense.

How Dimension Funding Structures EMR Financing

Dimension Funding finances EHR and EMR software for practices, clinics, and hospitals, with application only financing available up to $500,000 and no financial statements required at that level. The financing can include the software license, implementation and training costs, third party consultants, and related medical equipment or IT hardware, all combined into one fixed monthly payment.

Approvals are typically issued within a few hours, with funding often arriving the same day or within 48 hours, and terms extend out to give practices room to match the payment to the system’s expected lifespan. 

Financing works with the vendor of your choice, covering both traditional licensed EHR systems and cloud based SaaS platforms. Most equipment and software purchases also qualify for a Section 179 write off, which is worth reviewing with your accountant since it can bring the project’s cost below the sticker price.

Planning Your EMR Transition

Get a complete quote from your vendor before you apply for financing, one that includes implementation, training, and data migration rather than just the software license. That number is what a lender needs to structure the right amount of financing for the full project.

Decide early on a cloud based platform versus a traditional licensed system, since that choice affects both the ongoing subscription cost and how much hardware you’ll need on site. Build in time for staff training rather than assuming go live day is the finish line. 

Adoption, not the install date, is usually what determines whether a new EMR system improves clinical operations or just adds a layer of frustration.

Consider a phased rollout if your practice has multiple providers or locations, training a small group first and letting them help the rest of the staff once the system is live. It slows the initial timeline slightly but tends to reduce the disruption to patient scheduling during the switch.

Use a payment calculator to see what a given financing amount translates to as a monthly payment before you commit, so the number fits comfortably alongside your practice’s other expenses.

Frequently Asked Questions

What does EMR financing typically cover?

A well structured program covers more than the software license. It can include implementation and configuration, staff training, data migration, hardware like tablets or servers, and any third party consultants involved in the rollout, all combined into one payment.

Do you need financial statements to finance an EMR system?

Not always. Application only financing is available up to $500,000 for medical software, including EHR and EMR systems, without requiring financial statements at that level. Larger amounts require some financial documentation, though the process still moves quickly.

How fast can a practice get approved for EMR financing?

Approvals are typically issued within a few hours, with funding often arriving the same day or within 48 hours. That speed matters when an outdated system is already slowing down clinical work and a practice wants to move on a replacement without delay.

Can EMR financing be used for a cloud based or SaaS system?

Yes. Financing works with the vendor of your choice, whether that’s a traditional licensed EHR or a subscription based cloud platform. The ongoing subscription cost and any implementation or training tied to it can be structured into the financing as well.

Is EMR or EHR software eligible for a Section 179 write off?

Most equipment and software purchases qualify, which can bring the system’s cost below its sticker price. The specifics depend on your practice’s tax situation, so it’s worth reviewing with your accountant before you finalize a purchase.

Does financing an EMR system slow down the transition?

No, it typically speeds things up. Since the full project, software, implementation, training, and hardware, gets bundled into a single approval, a practice does not have to wait on separate cash outlays for each piece before starting the rollout.

Talk to a Financing Expert Before You Switch

An EMR switch is disruptive enough without also worrying about how to pay for it all at once. Dimension Funding has been financing medical software and equipment for practices, clinics, and hospitals since 1978, working with almost all credit types and almost any EHR or EMR vendor.

If you’re planning a transition, find out what the whole project, software, implementation, training, and hardware, would cost as a single monthly payment. Request a quick financing quote or call 1.800.755.0585 to talk it through with a financing expert.

Equipment Financing for Startups: How New Businesses Secure Funding

equipment financing for startups

Equipment Financing for Startups: How New Businesses Secure Funding

You need a walk-in cooler before you can open the restaurant, a delivery van before you can take on clients, or a set of machines before you can produce anything at all. That’s the catch built into starting a business: the equipment usually has to come first, before there’s any revenue history to point to. 

Most equipment lenders want to see a year or two in business before they’ll talk rates. So where does that leave a company that opened its doors six months ago, or hasn’t opened them yet?

That leaves you with fewer lenders to choose from, but more options than most new founders assume. Equipment financing for startups happens every day. It just works differently than it does for an established company, and knowing what a lender is checking for is what separates a quick approval from a string of declines.

Why Startups Have a Harder Time Getting Approved

Equipment lenders price risk based on what they can verify. An established business has tax returns, bank statements, and a payment history that shows how it handles debt. A new business has none of that yet, so a lender has no track record to lean on and has to make a decision based on thinner information.

That doesn’t mean startups are unfundable. It means the underwriting shifts toward what a lender can verify even without years of history: the owner’s personal credit, how much cash is going into the deal up front, and how easily the equipment itself could be resold if something went wrong.

What Lenders Look at Instead of Time in Business

Personal credit and a personal guarantee

When a business doesn’t have its own credit history, the owner’s personal credit becomes the main signal a lender has to work with. Most equipment financing applications for newer businesses include a section for a personal guarantee, where an owner agrees to stand behind the debt personally. It’s a standard part of underwriting a new business, not a red flag. A strong personal credit score can offset a thin business file.

Down payment size

Putting more money down lowers the lender’s exposure, which matters more when there’s no business history to fall back on. A startup that can put 10 to 20 percent down is usually in a stronger position than one asking for full financing with nothing down.

Industry and equipment type

Equipment that holds its value and has an active resale market, like commercial kitchen equipment, trucks, or general purpose IT hardware, is easier to finance than something narrow and hard to resell. Lenders are more comfortable when they know the equipment could recover most of its value if they ever had to repossess and sell it.

Monthly revenue, even if it’s new

Even a business open a few months can show early revenue through bank statements. A young company with steady monthly deposits has a stronger case than one with no transaction history at all, even if the numbers are modest.

Where New Businesses Get Approved

Vendor financing. Many equipment manufacturers and dealers work directly with financing companies to offer funding at the point of sale. Because the vendor already has a relationship with the lender, this path can be more accessible for a new business than walking into a bank cold.

Application only programs. Some financing companies will approve equipment purchases up to a set amount without requiring tax returns or financial statements, relying instead on the application, personal credit, and a personal guarantee. This is often the fastest route for a newer business that doesn’t have years of financials to submit.

SBA microloans. For very small equipment purchases, SBA microloan programs are built with newer businesses in mind and are more flexible on operating history than a conventional bank loan, though the approval process tends to move slower than private financing.

Specialty and alternative lenders. Lenders that focus specifically on newer or smaller businesses tend to weigh personal credit and industry experience more heavily than time in business, which is good news if you don’t have two years of tax returns to show.

Equipment leasing. A lease can be easier to qualify for than a loan because the lender retains ownership of the equipment for the term, which lowers its risk. For a startup trying to keep cash free for payroll and inventory, a lease often means a smaller upfront cost than a purchase, with the option to buy, upgrade, or walk away once the term ends.

What This Looks Like at Dimension Funding

Dimension Funding works with almost all credit ratings, from strong to marginal, and finances businesses from $5,000 up to $10 million or more. The application asks for your date to be established, but it also includes a section for a personal guarantee, information that can support a newer business that doesn’t have years of financial statements behind it.

Should your equipment come through a vendor that already partners with Dimension Funding, you may also be able to arrange financing directly at the point of sale. 

For businesses needing more than equipment, a working capital loan can cover early costs like inventory or payroll, though these typically carry higher rates and more requirements than financing tied to a specific piece of equipment.

Approvals are usually issued within a few hours, with funding often arriving the same day or within 48 hours, which matters when you’re a new business that needs the equipment running now, not next month.

Getting Ready to Apply

Pull your personal credit report before you apply and fix anything that’s wrong on it. This is the number lenders lean on most, so it’s worth knowing what they’ll see before they do.

If you can, set aside some cash for a down payment. Even a modest amount down tells a lender you’re invested in the deal yourself, and it can open up better terms than asking for full financing with nothing up front.

Get a firm quote from your equipment vendor first, with a specific make, model, and price. That gives a lender something concrete to evaluate instead of a vague request, and it speeds up the whole process.

Consider starting smaller. Financing one essential piece of equipment and building a payment history can make the next, bigger purchase easier to finance, whether that’s with the same lender or a different one down the road.

Talk to your accountant about Section 179 before you buy. Many equipment purchases qualify for a write off in the year you buy them, which can meaningfully lower the real cost of financing for a business watching every dollar in its first year.

Have your paperwork in order as well: a federal ID number, a business bank account, and proof of your business structure. Lenders notice when that’s already been handled.

Frequently Asked Questions

Can a startup with no business history get equipment financing?

Yes. Lenders lean more heavily on the owner’s personal credit, a personal guarantee, and the down payment when there’s no business track record to review. A brand new business is not automatically disqualified, it just gets underwritten differently than an established one.

How much down payment does a startup need for equipment financing?

It varies by lender, but putting down 10 to 20 percent is a reasonable starting point for a business without an operating history. A larger down payment lowers the lender’s risk and can help offset a thin business file.

Do startups have to personally guarantee equipment financing?

Often, yes. Most equipment financing applications for newer businesses include a section for a personal guarantee, where the owner agrees to stand behind the debt. It’s a standard part of underwriting a new business rather than a sign that something is wrong with the deal.

Is equipment leasing easier to get than an equipment loan for a new business?

It can be. Since the lender retains ownership of the equipment during a lease term, its risk is lower, which sometimes makes leasing more accessible for a business without years of financials. It also tends to require less cash upfront than an outright purchase.

How fast can a new business get approved for equipment financing?

Through application only programs, approvals are often issued within a few hours, with funding arriving the same day or within 48 hours. Financing that requires full financial statements typically takes longer to process.

What credit score does a startup need to finance equipment?

There is no single number that applies everywhere, since lenders weigh credit score alongside the down payment, the equipment type, and any early revenue. Programs that work with a wide range of credit profiles, from strong to marginal, exist specifically because newer businesses rarely have a long credit history to show.

Talk to a Financing Expert Before You Assume You Don’t Qualify

A lot of new business owners rule themselves out of equipment financing before they even apply, assuming that no track record means no approval. That’s rarely true. What you qualify for comes down to your personal credit, your down payment, and the equipment itself, and the only way to know where you stand is to ask.

Dimension Funding has been financing equipment and software for small businesses since 1978, working with almost all credit types across industries from restaurants and construction to medical offices and IT. 

If you’re a new business trying to figure out what you qualify for, fill out a quick financing application or call 1.800.755.0585 to talk it through with a financing expert.

Equipment Financing Rates in 2026: What Interest Rate to Expect?

equipment financing rates

Equipment Financing Rates in 2026: What Interest Rate to Expect?

If you’ve been shopping for equipment financing, you’ve probably noticed that no two lenders quote the same number. 

One bank comes back at 7 percent, an online lender quotes 18 percent, and a leasing company skips the rate conversation entirely and just hands you a fixed monthly payment. That spread leaves a lot of business owners stuck on one question: what rate should you actually expect to pay in 2026?

There’s no single answer, and anyone who gives you a flat number without asking about your business first is skipping steps. Your rate depends on your credit profile, how long you’ve been operating, the type of equipment involved, and which kind of lender you approach. 

Once you know how those pieces fit together, you can sit down for a financing conversation and tell whether the offer in front of you is actually fair.

What Actually Determines Your Equipment Financing Rate

A lender isn’t guessing when it hands you a number. A handful of factors do most of the work.

Your credit history

Personal and business credit is usually the first thing an underwriter looks at. Strong credit doesn’t just improve your odds of approval, it unlocks the lower end of the rate range. Businesses with marginal or limited credit still get approved often, just at a higher rate that offsets the lender’s added risk.

Time in business and revenue

A company with several years of steady revenue reads as a safer bet than a brand new operation, and the rate reflects that. Newer businesses can still qualify, but should expect a few extra points added to the quote until they build a track record.

Equipment type and age

Financing for new equipment with strong resale value, like a delivery vehicle or a piece of medical equipment, tends to price better than financing for older or specialized equipment that would be hard to resell if a deal fell apart.

Loan term and amount

Shorter terms generally carry lower rates. Longer terms spread the payment out but can add cost over the life of the agreement. The financing amount plays a role too. Larger requests sometimes earn better pricing, though they may call for more documentation up front.

Down payment

Putting money down reduces the lender’s exposure and can shave points off your rate. Many equipment financing programs don’t require one at all, which is part of the appeal, but a modest down payment can still improve your terms if your budget allows for it.

Equipment Financing Rates in 2026: What the Ranges Look Like

Rates move with the broader economy, but the order between lender types tends to hold steady from year to year.

Banks and credit unions typically offer the most competitive pricing on commercial equipment financing, often between 6 and 12 percent for borrowers with strong credit and an established history. The tradeoff is a slower process, more paperwork, and stricter approval standards.

SBA backed programs can push rates even lower, sometimes into the 5 to 10 percent range, but they come with tighter credit requirements and a longer timeline that doesn’t always fit a business that needs equipment running this month.

Alternative and direct lenders move faster and work with a wider range of credit profiles. Rates through these channels commonly fall between 10 and 25 percent, depending on the strength of the borrower and the specifics of the deal.

Put together, a well qualified borrower using a bank, credit union, or SBA program can expect a rate around 6 to 14 percent. A business with a shorter operating history or less than ideal credit should expect a rate toward the higher end of the overall range, sometimes above 20 percent, particularly through faster alternative channels.

How the 2026 Rate Environment Factors In

The Federal Reserve has held its benchmark rate steady through the first half of 2026, and the prime rate lenders use as a starting point has followed along. That stability is good for planning. A quote you get this quarter probably won’t look dramatically different three months from now, so there’s less reason to rush a decision purely out of fear that rates will jump overnight.

That doesn’t mean every lender is standing still. Underwriting standards, seasonal promotions, and how badly a particular lender wants new business all move the number you get quoted, often more than the benchmark rate itself does. Comparing more than one offer still matters, even when the broader rate environment is calm.

Fixed Rate Versus a Rate Tied to the Market

Most equipment financing and leasing arrangements use a fixed rate for the full term, so your payment stays the same from the first month to the last. That’s different from a variable rate credit line, where payments move as the market shifts.

A fixed rate gives you a number you can actually plan around for budgeting and cash flow. That predictability is why it’s the standard structure for equipment financing, not a feature you have to ask for.

Loans vs Leases: Does the Rate Work the Same Way?

Equipment loans and equipment leases get compared using different math. A loan has a straightforward interest rate attached to it. 

A lease is often quoted as a payment factor or bundled into one monthly number that already reflects the cost of financing, so a lease payment and a loan rate aren’t always apples to apples on paper.

That doesn’t make one automatically cheaper than the other. A loan builds equity in the equipment from day one and tends to make sense if you plan to keep it long term. 

A lease can lower the monthly payment and may bundle in maintenance or upgrade options, which matters more for equipment that ages out fast, like certain IT hardware. The right structure depends on how long you plan to actually use the equipment, not just which number looks smaller.

How to Position Your Business for a Better Rate

Clean up your credit before you apply, if you have time. Even a modest score improvement can move you into a better pricing tier.

Have your basic financials organized, even for application only programs. A clear answer to a lender’s questions speeds up approval and supports a stronger offer.

Think about term length. A shorter term often earns a better rate, but the payment still needs to fit comfortably into your monthly cash flow.

Get more than one quote. Shopping for equipment financing typically doesn’t affect your credit the way shopping for many consumer loans does, and a second quote gives you real leverage in the conversation.

Why the Rate Isn’t the Only Number to Watch

The interest rate is only part of the cost picture. Through Dimension Funding, businesses can get application only financing up to 250,000 dollars for equipment and up to 500,000 dollars for software, meaning no financial statements are required to get an answer. 

Financing can cover 100 percent of the project, including delivery, installation, and maintenance, so those costs don’t come out of your pocket separately. Terms run from 12 to 60 months, giving you room to match the payment to how long the equipment will actually generate revenue for your business.

Most equipment purchases also qualify for a Section 179 write off, which can lower the after tax cost of financing below what the sticker rate suggests. Run the numbers with your accountant before you finalize a purchase, and use the payment calculator to see what a given rate actually means for your monthly payment.

A slightly higher rate paired with same day approval, a longer term, and maintenance built into the payment can cost less in practice than a lower rate that takes weeks to close and leaves you covering installation on your own.

Frequently Asked Questions

What is a good interest rate for equipment financing in 2026?

Anything in the 6 to 14 percent range is strong for a well qualified borrower going through a bank, credit union, or SBA program right now. Rates above 20 percent aren’t unusual for businesses with a shorter operating history or credit challenges, especially through faster alternative lenders.

Can you get equipment financing with bad credit?

Yes. Most equipment financing programs work with a wide range of credit profiles, including marginal or limited credit. The tradeoff is usually a higher rate rather than an outright decline, since the higher rate offsets the lender’s added risk.

Do you need a down payment for equipment financing?

Not always. Many programs are structured without a large down payment, which helps preserve working capital. Putting money down is optional in most cases, though it can improve your rate if your budget allows for it.

Is equipment financing tax deductible?

The equipment itself may qualify for a Section 179 write off, which can let you deduct a significant portion of the purchase in the year you buy it instead of depreciating it over time. Talk to your accountant about how this applies to your specific purchase and financing structure.

How fast can you get approved for equipment financing?

Approvals are often issued within a few hours for application only programs, with funding arriving the same day or within 48 hours. Larger financing amounts that require full financials take a bit longer, but still move faster than most traditional bank loans.

Does shopping for equipment financing hurt your credit?

Generally, no. Getting quotes from multiple equipment lenders typically doesn’t affect your credit the way shopping for personal loans or credit cards can, so comparing more than one offer before you commit is a reasonable thing to do.

Getting Your Actual Rate Quote

Every number in this article is a range. The only way to know what your business will actually pay is to apply and let a lender underwrite your specific credit, revenue, and equipment.

Dimension Funding has been financing equipment and software for small and medium sized businesses since 1978, working with almost all credit types across industries including construction, medical, restaurant, brewery, and IT technology equipment. Approvals are typically issued within a few hours, with funding often arriving the same day or within 48 hours.

If you want a clear answer on what rate and payment your business qualifies for, request a quick financing quote or call 1.800.755.0585 to talk through your options with a financing expert.