Remanufactured Equipment Vendor Programs | Dimension Funding

Remanufactured Equipment Vendor Programs

Remanufactured Equipment Vendor Programs | Dimension Funding

Remanufactured equipment is rebuilt to original manufacturer specifications, not simply repaired or resold, and that distinction changes how a lender looks at the collateral compared to ordinary used equipment.

Dimension Funding finances new and used equipment on the same application-only basis, up to $250,000 for equipment alone and $500,000 when software is part of the deal, and that structure extends to remanufactured units without a separate approval track. Most remanufacturers already know financing exists. What they need to know is whether a rebuilt unit gets treated the same way a new one does. 

The backdrop is a large and steady replacement cycle. The global off-highway vehicle engine market, covering construction, agricultural, and mining equipment, stood at $47.94 billion and is projected to reach $66.21 billion by 2031, according to Mordor Intelligence, driven by replacement cycles and emission-compliance retrofits that keep older machines in service longer.

Alongside that sits a related but distinct market: machinery maintenance and heavy equipment repair services in the US reached $59.9 billion in 2025, per IBISWorld. Keeping aging equipment running, whether through repair or a full rebuild, is a large and active part of the economy, not a niche behind new-equipment sales. 

The Programs Available to Remanufacturers

Remanufacturers draw on the same core set of programs as any other equipment vendor, applied to a category of collateral that behaves differently on paper. Standard equipment financing covers the rebuilt unit itself, zero percent financing is available as a vendor-sponsored option, and working capital loans run separately, funding the vendor’s own operation rather than a specific sale.

Dimension Funding generally prefers at least two years in business from the applicant, whether that’s a remanufacturer financing its own shop equipment or a buyer financing a purchase from one, though strong credit can substitute for a shorter history. Credit requirements themselves are flexible too, covering most types from strong commercial credit down to marginal, which matters for a newer rebuild shop or a buyer whose credit took a hit during a slow stretch.

Why Remanufactured Equipment Isn’t Financed Like Ordinary Used Equipment

A machine that’s simply used has depreciated in an uneven, hard-to-predict way, which is part of why lenders often ask for more documentation on it. A remanufactured unit has gone through a controlled teardown-and-rebuild process to original specification and typically carries a warranty comparable to a new unit’s, which gives the collateral a more predictable value profile than a random used machine of the same age.

That’s why remanufactured equipment can usually support the same term lengths available on new equipment, up to 60 months, rather than the shortened terms a lender might apply to equipment nearing the end of its useful life.

Financing a Component vs. a Whole Unit

A significant share of remanufacturing happens below the level of a complete machine: engines, transmissions, and hydraulic pumps rebuilt and installed into equipment the buyer already owns, rather than sold as a standalone unit. That changes what gets financed. The component going into the machine, plus the labor to remove the old one and install the rebuild, is the asset, not the host machine itself. 

That distinction carries into the tax treatment too. A rebuilt component installed into equipment the buyer already owns is itself the qualifying property for Section 179 purposes, not the host machine, so the deduction is based on what the component and its installation cost, not the original price of the machine it’s going into. 

Section 179 and Bonus Depreciation on Remanufactured Equipment

Per IRS Publication 946, the 2026 Section 179 limit is $2,560,000, phased down once qualifying purchases exceed $4,090,000, and it applies to remanufactured equipment the same as new. Dimension Funding covers the current-year figures under Section 179 and how the deduction applies to financed equipment.

Bonus depreciation carries a separate wrinkle worth knowing before a buyer assumes both deductions work identically. Since the 2017 Tax Cuts and Jobs Act, bonus depreciation applies to used property only if it wasn’t used by the taxpayer or a predecessor at any time before the acquisition. A buyer who sends in their own worn unit as the core and receives back the remanufactured version is arguably reacquiring equipment they already had a depreciable interest in, which can put that specific transaction’s bonus depreciation eligibility in question even though Section 179 wouldn’t carry the same restriction. That’s a detail worth flagging to a buyer’s accountant before the deduction gets assumed rather than confirmed.

Stacking the 90-Day Deferral With the Tax Deduction

A remanufactured unit purchased and financed through Dimension Funding can also use the No Payments for 90 Days promotion, which lets a buyer take delivery, put the rebuilt unit to work, and wait 90 days before the first payment is due.

That timing lines up with the tax question above. A buyer can place a qualifying rebuilt unit in service, start claiming Section 179 or bonus depreciation for the year, and do both before making a single payment on it. For a buyer weighing a rebuilt unit against a full-price new one, that combination often closes the gap in ways a straight price comparison doesn’t capture.

Zero Percent Financing for Remanufactured Equipment Vendors

Remanufactured equipment already competes on price against two different sellers at once: new-equipment dealers arguing full capability justifies full price, and other remanufacturers rebuilding the same models. A zero percent offer lets a vendor hold the line on the sale price instead of discounting the unit itself to win a price-sensitive buyer.

Setting one up runs through Dimension Funding’s vendor partner application, the same starting point for any vendor financing arrangement, and from there the promotion can be scoped to specific product lines rather than applied across the board.

Bringing a Remanufacturing Program Online

None of this asks a remanufacturer to restructure how a rebuild gets quoted or sold. It asks for a financing partner that treats a remanufactured unit’s collateral value the way the rebuild process earns it, rather than defaulting to the documentation and term-length assumptions built for ordinary used equipment.

A vendor can run a sample deal through Dimension Funding’s payment calculator or start an application directly. Contact Dimension Funding to talk through what a vendor program would look like for a specific remanufactured product line.

Frequently Asked Questions

Does equipment need to come from an OEM-certified remanufacturing program to qualify, or does independently remanufactured equipment qualify too?

Dimension Funding’s equipment financing applies broadly to new and used equipment without requiring a specific certifying body, so independently remanufactured equipment qualifies on the same basis as an OEM-authorized rebuild, provided documentation on the rebuild itself is available with the application.

Is the 90-day payment deferral available on any remanufactured unit, or does it depend on the product line?

It’s generally available across financed equipment and software, though exceptions apply, so it’s worth confirming eligibility for a specific remanufactured product line before assuming it’s included in a given deal.

Can financing on a remanufactured unit include the remanufacturer’s own warranty or an extended service plan, not just the equipment itself?

Yes. Associated costs including installation, labor, and maintenance can be bundled into the same fixed payment as the equipment, and a remanufacturer’s own warranty or service plan can be included the same way rather than billed as a separate line item.

Can a remanufacturer use working capital financing for its own operation, such as sourcing cores or building inventory, separate from financing a specific buyer’s purchase?

Yes. Working capital loans, available from $25,000 to $250,000 for businesses with annual revenue above $150,000, are structured around the business itself rather than a specific transaction, which makes them usable for a remanufacturer’s own operating needs rather than only for financing a buyer’s equipment purchase.

Do the same application-only thresholds, $250,000 for equipment and $500,000 with software included, apply to remanufactured equipment as they do to new equipment?

Yes. The application-only thresholds apply based on transaction size and structure, not on whether the equipment is new, used, or remanufactured, so a remanufactured unit financed on its own or bundled with software qualifies under the same limits.

Is a remanufactured unit financed only as a purchase, or can it be structured as a lease the same way new equipment can?

Both structures are available. Dimension Funding offers equipment leasing alongside standard finance agreements, and a remanufactured unit can go through either one the same way a new unit would, depending on whether the buyer wants ownership at the end of the term or lower payments with the option to upgrade.

Can a remanufacturer finance the equipment used to run its own rebuild operation, such as test benches or diagnostic tooling, separately from financing a buyer’s purchase?

Yes. That equipment is financed the same way any other commercial equipment purchase would be, with the remanufacturer as the applicant rather than the buyer. It’s a separate transaction from financing offered to a customer purchasing a rebuilt unit, though both can run through Dimension Funding.

Compact Track Loader Financing: Rates, Leases & Cost Considerations

Compact Track Loader Financing

Compact Track Loader Financing: Rates, Leases & Cost Considerations

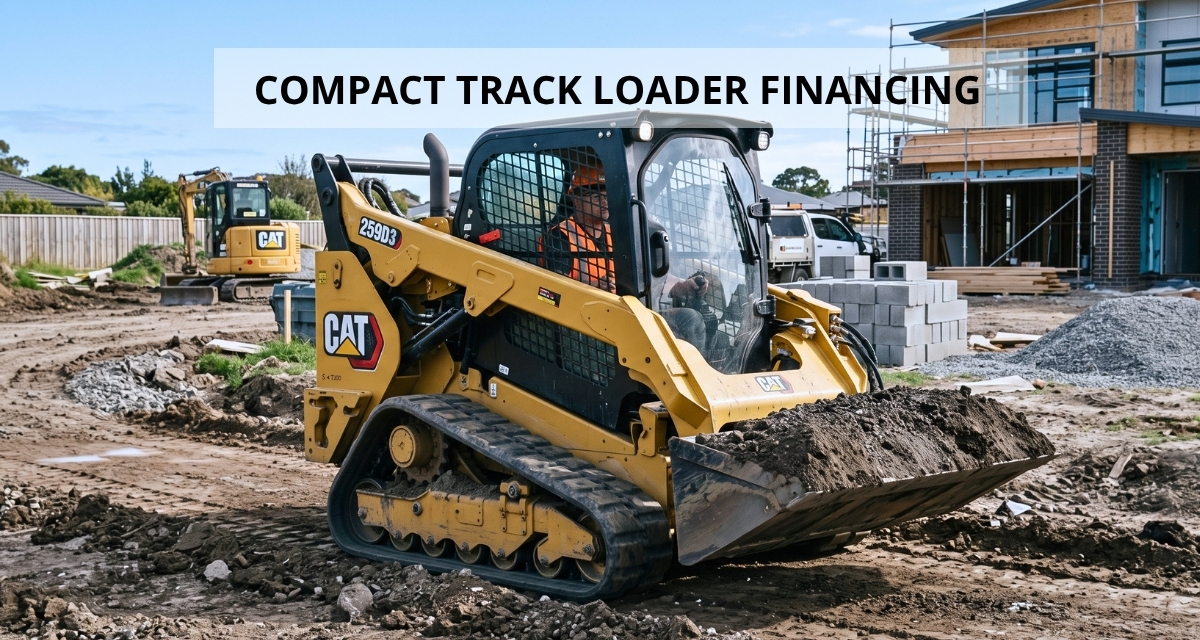
Compact track loader financing exists because the machine costs more than a skid steer to begin with, and running rubber tracks over rough ground adds ongoing costs a wheeled machine doesn’t carry. 

New John Deere models alone range from $60,000 to $150,000 depending on size and configuration, according to RDO Equipment’s 2026 CTL pricing breakdown. Add a set of tracks at $2,000 to $4,000 installed, and the total climbs past what most contractors want on one invoice.

Dimension Funding finances construction equipment, including compact track loaders, for businesses across the U.S. Your loan or lease can run up to 60 months, and approval on amounts up to $250,000 can come from the credit application alone, no financial statements required. 

Sign electronically, and funding can clear the same day, quick enough that a loader you’re ready to buy doesn’t turn into one you have to keep shopping for.

What Compact Track Loader Financing Covers

A loan builds toward owning the machine outright. A lease spreads the cost of using it over a fixed period instead, and you decide what happens to it once that period ends. Either structure works whether the loader is new off the lot or already has hours on the meter.

Dimension Funding has written equipment financing since 1978. A track loader purchase usually starts with a specific job, not a plan. Soft or sloped ground shows up on a contract, a wheeled machine can’t handle it, and that’s what triggers the order.

Loan or Lease for a Compact Track Loader

The monthly figure can land close either way. What’s different is what you’re left holding when the term ends. A loan finances the purchase, so the machine is yours once it’s paid off. A lease finances the use of it for a set period, and ownership only happens if you buy it out afterward.


Loan

Lease

Ownership

Yes, once paid off

Not automatic

End of term

Loader owned outright

Return, buy out, or upgrade

Best fit

Work that keeps the machine busy year round

Jobs or terrain needs that shift season to season

Payment basis

Reflects the full purchase price

Reflects the value used during the term

How a Loan Works

The lender pays the purchase price upfront. You repay it in fixed monthly installments, and the loader is yours from the day the loan closes, subject to the lender’s lien until the balance clears. There’s nothing to negotiate when the term ends, because you already own the machine.

How a Lease Works

Lease payments get priced against how much value the loader loses during the term, not its full purchase price. That’s why two contractors financing the same model can end up with different monthly numbers if their terms don’t match.

When the lease ends, you can buy the loader at a price set when you signed, hand it back, or move into a newer model. Running the same loader through wet season after wet season is a different bet than trading up for a lower hour machine every couple of years.

Compact Track Loaders vs Skid Steers: Where the Costs Diverge

Tracks are the reason a compact track loader costs more than a skid steer to buy, and more to keep running. Skid steer tires run $150 to $400 each. A set of rubber tracks costs $500 to $1,400 per track, or $2,000 to $4,000 installed as a full set, according to Machinery List’s 2026 track replacement cost guide. Budget $1.50 to $3.00 per operating hour for track wear, since most sets last 1,200 to 2,000 hours before they need replacing.

What you get for that premium is traction. Tracks spread a loader’s weight across a wider footprint, so it holds up on soft, muddy, or sloped ground where a skid steer would spin its wheels or sink. 

Skid steers answer back with lower running costs and tighter turns on concrete or compacted gravel, according to Skid Pro’s comparison of the two machine types. Ground conditions decide this one more than price does.

What a Compact Track Loader Costs

Pricing by Size and Configuration

New John Deere compact track loaders range from about $60,000 to $150,000 depending on size and setup, with the 317P around $62,000 and the larger 335P closer to $122,000, according to RDO Equipment’s pricing breakdown. Similar spreads apply across Bobcat, Caterpillar, and Kubota lineups once you compare equivalent horsepower and operating weight.

Cab upgrades add $5,000 to $50,000 depending on climate control and technology. Attachments run $1,500 to $40,000 or more on top of that, per the same source. Start with a $70,000 loader, add an enclosed cab and a grapple, and you’re financing closer to $100,000 by the time it’s all added up.

Where Financing Activity Stands This Year

More than 56,000 new compact track loaders were financed nationwide between May 2025 and April 2026, up 1.2 percent from the year before, according to Equipment World’s tracking of financed sales. Kubota led new financing at 27.1 percent, with Caterpillar close behind after an 18.8 percent jump in volume.

Used financing grew faster, up 8.7 percent to roughly 21,000 units, with Bobcat leading that segment at 23.3 percent. Average used pricing eased to $55,380 in the first quarter of 2026. The typical unit financed was 5.2 years old.

What Changes Your Payment

Term Length and Equipment Age

Push the price up or shorten the term, and the monthly payment climbs. Stretch the term out and it drops, but you risk paying on a machine after the tracks and undercarriage are already worn past their useful hours. Dimension Funding runs terms as long as 60 months, which usually lines up with how long a well maintained loader keeps earning its keep.

Buying New vs Buying Used

New loaders qualify for longer terms, since there’s more working life ahead of them. Go with a used unit, especially one already showing track wear, and the term shortens to match what’s realistically left in the undercarriage.

Approval Requirements for Compact Track Loader Financing

What Moves on the Application Alone

Up to $250,000, the credit application alone is enough for approval, no financial statements needed. That threshold covers most single machine purchases and plenty of two or three loader orders for a growing fleet. Go above it, and underwriting will ask for recent financials before funding closes.

Credit Profiles Dimension Funding Works With

Dimension Funding underwrites credit profiles from strong tier A down to marginal rather than applying one cutoff for every applicant. Approval commonly comes back within hours when the application and signatures are handled electronically, with funding following in a day or two. A used loader at a good price rarely waits around for a slow approval.

Financing That Matches How Long the Tracks Will Last

Every compact track loader starts running down a clock the day it goes to work. Tracks wear toward that 1,200 to 2,000 hour replacement mark no matter what the financing term says, 36 months or 60. Match the term to that clock, not to whichever number drops the payment most. Do that, and you won’t end up paying on a loader that needs a new undercarriage before the loan is done.

Dimension Funding can walk through what financing a specific loader, new or used, looks like against the job it’s buying for. Worth having that conversation before the term gets picked for you by whatever number looks smallest on the quote.

Frequently Asked Questions

Will a lender finance a compact track loader that already has hours on it?

Yes, most equipment lenders finance compact track loaders with hours already logged as readily as units straight off the lot. Used financing grew faster than new financing over the past year, up 8.7 percent versus 1.2 percent, according to Equipment World’s 2025 to 2026 tracking. The term shortens to match whatever working life is left in the undercarriage.

What credit score do I need for compact track loader financing?

There’s no fixed score that decides approval by itself. Dimension Funding weighs your business history alongside personal credit, with programs running from strong tier A down to marginal, and on amounts up to $250,000 that review can happen straight from the application.

How long are typical compact track loader loan or lease terms?

Terms commonly run up to 60 months. Where your loader lands in that range depends on whether it’s new or used and how many hours are already on the tracks, since financing one well past its realistic working life rarely makes sense.

How do I decide between a loan and a lease if my jobs don’t always need a track loader’s traction?

Base the decision on how often the ground calls for tracks, not on the monthly payment alone. Lease if soft, muddy, or sloped terrain only shows up on some jobs, since you avoid paying to maintain tracks between the jobs that don’t need them. Buy outright once that kind of ground shows up often enough to keep the loader working most weeks.

Can attachments and cab upgrades be rolled into the same financing as the loader?

Yes, most lenders bundle attachments and cab upgrades into the same loan or lease as the base machine. That matters here more than with some equipment, since a grapple or an enclosed cab can add tens of thousands to the total cost, and financing the full package keeps the payment tied to what you’re driving off the lot.

How does financing a compact track loader differ from financing a skid steer?

The financing structure is the same, a loan or a lease with terms up to 60 months either way. What changes is the amount, since a compact track loader typically costs more upfront than a comparable skid steer and carries higher ongoing track replacement costs that are worth factoring into the term you choose.

How fast can compact track loader financing be approved?

Approval can come back within hours when the application and signatures are handled electronically, with funding following in a day or two. That turnaround matters most on a used loader, where a specific price on a specific machine tends to move fast once it’s listed.


Bucket Truck Financing: Reliable Solutions for Utility & Tree Care Crews

Bucket Truck Financing

Bucket Truck Financing: Reliable Solutions for Utility & Tree Care Crews

Bucket truck financing splits the cost of a $140,000 insulated unit into a monthly payment sized to what the truck can bring in, not what’s sitting in the bank right now. A 55 foot insulated model runs that price new and about $85,000 used, and a 75 foot material handler starts near $170,000 new, per The Upfit Insider’s bucket truck pricing guide.

Pay cash for one instead, and the truck usually sits on a wish list while a storm restoration contract, or a backlog of tree removal jobs, waits for it.

Dimension Funding finances bucket trucks and other utility and tree care vehicles for businesses across the U.S., from a single replacement unit to a full crew build out. Purchases up to $500,000 can be approved from the credit application alone, and financing runs as high as $10 million or more for larger fleet builds.

Sign electronically and funding can go through within a day or two, so a truck already lined up for a scheduled job doesn’t sit on the lot waiting on approval.

What Bucket Truck Financing Covers

Bucket truck financing covers two structures: a loan that builds toward ownership of the truck, or a lease that spreads the cost of using it over a fixed period. Either one can apply to insulated units built for electrical utility work, non insulated units for tree care and signage crews, or material handlers built for heavier lifts.

Dimension Funding has financed commercial vehicles since 1978, long enough for its underwriting to account for how utility and tree care crews buy in practice. Not on a fixed replacement schedule, but when a contract lands, storm season approaches, or an aging unit finally fails its annual dielectric test.

Loans vs Leases for Bucket Trucks: What Changes

Same monthly payment, different truck at the end of it. A loan finances the purchase, so you own the bucket truck once the term is paid off. Lease the same truck instead, and ownership isn’t part of the deal unless you buy the unit separately once the term is up.

Crestmont Capital’s equipment finance data puts loans at 44 percent of transactions nationally and leases at 38 percent, with lines of credit and sale leaseback arrangements splitting the rest.


Loan

Lease

Ownership

Yes, once paid off

Not automatic

End of term

Truck owned outright

Return, buy out, or upgrade

Best fit

Trucks run for years

Trucks likely to be upgraded

Payment basis

Reflects the full purchase price

Reflects the value used during the term

How a Bucket Truck Loan Works

The lender covers the purchase price of the truck. You repay it in fixed monthly installments, and the truck is yours from the day the loan closes, subject to the lender’s lien until it’s paid off. Once the last payment clears, it’s simply yours, free to keep running calls or sell once you move up to a taller boom.

How a Bucket Truck Lease Works

A lease prices your payment against how much value the truck loses over the lease term, not its full purchase price. That’s why a lease payment often comes in lower than a loan payment on the same unit.

At the end of the term, you return the truck, buy it at a price set when the lease began, or move into a newer model. A utility contractor running the same 55 foot unit for a decade has different priorities than a telecom crew that upgrades boom height every few years as job specs change.

Why Bucket Truck Prices Push Crews Toward Structured Payments

What Different Bucket Truck Classes Cost

Boom height moves the price more than the chassis it’s mounted on. A 40 foot non insulated unit, the entry point before insulation and extra reach push the number higher, runs $85,000 new and $50,000 used, per The Upfit Insider’s pricing breakdown.

$170,000 is roughly the starting point for a 75 foot material handler new, with used units closer to $110,000, and a track mounted unit built for soft ground access can run $200,000 or more. 

Each additional 10 feet of reach adds roughly $15,000 to $20,000 to the price, and hybrid PTOs or added hydraulic tool circuits add another $5,000 to $8,000 on top, according to the same source.

Demand for Aerial Units Keeps Climbing

Global Market Insights projects the global forestry equipment market, which includes the bucket trucks tree care crews rely on, to reach $17 billion by 2026, a figure cited by Custom Truck One Source.

Crestmont Capital’s utility truck financing guide puts federal broadband infrastructure investment at $65 billion, adding to that pressure on the utility and telecom side and pushing more line crews and cable contractors to add aerial units instead of renting them by the week.

What Shapes the Monthly Payment

Boom Height and Term Length

Go taller on the boom or shorter on the term, and your monthly payment climbs faster than you’d expect. Stretch the term out and the payment drops, but you could end up paying on a truck well past the years it’s realistically productive on the job.

Dimension Funding caps terms at 60 months, which usually lines up with how long a bucket truck holds up under regular annual inspection before major boom or hydraulic work costs more than the truck is worth.

New Condition vs Used Condition

New units support longer terms since there’s more working life ahead of them. Choose a used truck instead, especially one with heavy prior boom cycles, and your term shortens to match. The hours logged on the hydraulic system and the results of the last dielectric test matter as much as the model year.

Approval Requirements for Bucket Truck Financing

Application Only Thresholds

Most equipment lenders separate vehicle financing into tiers by dollar amount, and Dimension Funding follows that structure. You can move purchases up to $500,000 on the credit application alone, with no financial statements required.

Above that threshold, underwriting typically asks for recent tax returns and basic financials, and larger crew or fleet build outs can run past that point toward $10 million or more for established contractors.

Credit Profile and Documentation

A bank turning you down for a term loan doesn’t rule out bucket truck financing, since equipment lenders underwrite the truck almost as much as the business behind it. Crestmont Capital’s bucket truck financing data puts minimum credit around 550, with 650 or higher considered strong, and minimum annual revenue typically between $100,000 and $250,000.

Two or more years in business is preferred, though a strong contract backlog or established municipal work can offset a shorter track record.

Matching the Structure to How the Truck Will Be Used

The right structure usually comes down to how the truck fits your work, not which option looks cheaper on the quote. Buying a truck for one storm season has different math behind it than adding a permanent unit to your fleet. Usage, replacement habits, and resale plans tend to settle it:

  • Utilization matters most. A truck running daily service calls or line work usually points toward a loan.
  • Replacement habits vary by crew. Some run the same unit for a decade, others upgrade boom height or insulation rating as contracts change.
  • Resale only matters if you plan to own the truck outright. Otherwise, having a working unit on the lot is enough.

A loan tends to fit if the same truck runs daily calls for years. Contracts that shift in scope, or a crew expecting to move up in boom height as bigger jobs come in, point toward a lease instead. Even a mismatched choice rarely does real damage. You end up paying for flexibility you didn’t need, or owning a truck you’d rather have traded in for something newer.

Building a Bucket Truck Payment Around the Job, Not the Sticker Price

Parked at the yard, a bucket truck isn’t earning you anything, no matter how good the deal was. The sooner it’s on a job site running calls, the sooner the payment stops looking like overhead and starts looking like the reason you could take the contract at all.

Dimension Funding can walk through what a loan or a lease would look like for your specific truck and timeline before any paperwork gets signed. It’s worth a conversation before locking into either structure.

Frequently Asked Questions

Can I finance a used bucket truck, or only new units?

Most equipment lenders finance new and used bucket trucks side by side. A used unit typically gets a shorter term than a new one, since there’s less working life left on the boom and hydraulics to finance, but the purchase itself isn’t treated as a lesser option.

What credit score do I need for bucket truck financing?

No specific credit score guarantees approval, since lenders weigh your business history and contract backlog alongside your personal credit rather than applying a hard cutoff. Dimension Funding works with credit profiles across a wide range, from strong to marginal, rather than screening you out below a fixed number.

How long are typical bucket truck loan or lease terms?

Terms commonly run up to 60 months. The actual length depends on the truck’s boom height and condition, whether it’s new or used, and how long you plan to keep it in service.

Is leasing better than buying for a crew that upgrades boom height often?

Leasing fits better if you expect to upgrade equipment, since you’re not stuck holding an outdated unit once a bigger job calls for more reach. A loan makes more sense if the truck keeps doing the same work at the same boom height for years.

Does insulation testing or upfit work get financed along with the truck?

Yes, most equipment lenders roll upfit costs like insulation, hydraulic tool circuits, or hybrid PTOs into the same financed amount as the truck itself. That way the payment reflects the full working unit, not the base chassis price alone.

What happens at the end of a bucket truck lease?

At the end of a bucket truck lease, you can buy the truck at the price set when the lease began, return it, or roll into a newer model. A unit with years of working life left typically gets bought out, while one that a taller or newer boom would outperform is more often returned or upgraded.

How fast can bucket truck financing be approved?

Approval can come back within a few hours on purchases up to $500,000 when you handle the application and documents electronically. Funding typically follows within a day or two once the paperwork clears, which matters most when you need the truck for a storm response contract or a job that’s already scheduled.

Skid Steer Financing: Comparing Loans, Leases & Monthly Rates

Skid Steer Financing

Skid Steer Financing: Comparing Loans, Leases & Monthly Rates

Skid steer financing turns a machine that costs tens of thousands of dollars into a monthly payment you can plan for. A new mid-size unit runs past $50,000 before you even add attachments.

A used one in decent shape still clears $30,000 more often than not. Pay in cash and you tie up money you need for payroll, materials, or the next bid.

Dimension Funding finances construction equipment, including skid steers, for businesses across the U.S. Your loan or lease can run up to 60 months, and approval can move fast since it doesn’t always take a full set of financial statements to get a decision.

Sign the paperwork electronically and your funding can go through the same day. Find the right unit this week, and you’re not stuck waiting on it.

What Skid Steer Financing Covers

You’re choosing between two structures here: a loan that builds toward ownership, or a lease that spreads the cost of using the machine over a fixed period. Either one works for new or used equipment.

Dimension Funding has been financing equipment since 1978. That’s long enough for their underwriting to adjust to how contractors like you buy machines: in bursts, tied to a job, not on some long planning cycle.

Loans vs Leases: What Changes

The mechanics differ more than the monthly number on the page. A loan finances the purchase, so you own the skid steer once the term ends. A lease finances the use of the equipment for a set period, and what happens when that period ends is where the real difference from a loan shows up.


Loan

Lease

Ownership

Yes, once paid off

Not automatic

End of term

Machine is owned outright

Return, buy out, or upgrade

Best fit

Long term fleet additions

Equipment likely to be swapped or upgraded

Payment basis

Reflects the full purchase price

Reflects the value used during the term

How a Skid Steer Loan Works

The lender covers the purchase price. You repay it in fixed monthly installments, and the machine is yours from the day the loan closes, subject to the lender’s lien until you pay it off. No return process. No buyout decision at the end. Once your last payment clears, it’s simply yours.

How a Skid Steer Lease Works

A lease prices your payment against the equipment’s value over the lease term, not its full purchase price. That’s why a lease payment can look different from a loan payment on the same machine.

At the end of the term, you return the unit, buy it at a price set when the lease began, or roll into something newer.

Neither structure is the automatic right call. A landscaping company running the same skid steer for a decade has different priorities than a contractor who wants a newer, lower hour machine every couple of years.

Why Skid Steer Prices Push You Toward Structured Payments

What Different Size Classes Cost

Size class moves the number more than brand does. A small frame unit like the Bobcat S70 runs about $23,000 new and $18,300 used, according to Heavy Equipment Appraisal’s 2026 value guide.

Step up to a mid-size machine like the John Deere 312GR or Kubota SSV75, and new pricing lands between $50,600 and $54,500, with used units running $25,000 to $36,500 depending on hours. Komatsu’s comparable model prices close to $50,000 new and around $29,750 used, right in that same band.

High-output machines push higher still. The Caterpillar 226D3 and Case SV300 both list around $63,000 to $65,000 new, dropping to about $30,000 used. Know which class your job needs before you shop, since jumping one tier up can add $15,000 or more to what you’re financing.

Renting Against Financing

You might be weighing renting against financing too. The numbers explain why renting rarely wins beyond a short job. A skid steer typically rents for around $300 a day, $1,200 a week, or $3,000 a month, per the same Heavy Equipment Appraisal guide.

Keep renting for three or four months on a longer project and the total can pass what a loan payment would have cost. You’re left without a machine to show for it either way.

A rental still makes sense for a single week-long job or a one-off task. Financing pays off once the machine is earning its keep across more than one job.

Financing Activity Industry Wide

Financing activity across the equipment industry has been picking up as well. The Equipment Leasing and Finance Association’s Monthly Confidence Index climbed to 64.6 in January 2026, up from 58.3 the month before, inside a U.S. equipment finance market the association sizes at $1.3 trillion.

Skid steers are a small piece of that number, but the same math applies to your purchase too: a payment instead of a lump sum.

What Shapes Your Monthly Payment

Equipment Price and Term Length

A higher purchase price or a shorter term raises the monthly payment. Stretch the term out and the payment drops, but you could end up paying on a machine well past its most productive years.

Dimension Funding runs terms as long as 60 months, long enough to match your schedule to how much work the equipment still has left in it.

New Condition vs Used Condition

A new skid steer supports a longer term since it has more work ahead of it. Choose used, especially with higher hours already on it, and you’ll usually get financed over a shorter stretch. The hours on the meter matter as much as the age on the title.

What Attachments Add to the Financed Amount

Attachments change the number more than people expect. Pallet forks run $500 to $1,000, and a basic bucket adds another $750 to $1,000, according to Skid Pro’s pricing breakdown.

An auger lands between $2,000 and $2,500, and heavier attachments like brooms, trenchers, or stump grinders run $4,000 to $7,000 each. A dozer blade or snow plow sits in the same range, $3,000 to $6,000, per Skid Pro’s breakdown.

Buy a $50,000 skid steer with a $6,000 broom and a $2,000 auger, and you’re financing closer to $58,000, not $50,000. Roll attachments into the same loan or lease and the payment reflects the full package, not the base machine alone.

Credit Profile and Business Documentation

Skid steer financing doesn’t always ask for what a bank loan does. Dimension Funding can approve amounts up to $500,000 on the application alone, and works with most types of credit rather than requiring a long, clean financial history.

That matters most if you’re a newer business that hasn’t had time to build the track record a traditional bank usually wants before signing off on an equipment purchase.

New vs Used: How the Financing Picture Changes

Used skid steers aren’t a fallback option. They’re a normal part of how this equipment gets financed.

Bobcat led new unit financing with more than 28 percent of the market between May 2025 and April 2026, yet new volume overall slipped nearly 10 percent industry wide over that same stretch, according to Equipment World’s tracking of financed sales.

Deere and Case CE round out the next tier, each holding under 14 percent of new units financed over that stretch, per Equipment World’s brand breakdown. No single brand runs away with the used market either.

Used prices held closer to $39,900 on average in early 2026, well under what most new units run. If you’re cross-shopping, that gap changes your numbers fast.

Matching the Structure to How You’ll Use the Machine

The right structure usually comes down to how the equipment fits your business, not which option looks cheaper on paper. Buy a skid steer to run one long contract and the math looks different than keeping one around for whatever job shows up next. A few things tend to settle it:

  • Weekly hours matter. Run the machine daily, all season, and the math leans toward a loan.
  • Some businesses keep the same machine for years. Others trade in for something newer every time the job changes.
  • Resale only matters if owning the equipment outright is part of your plan. Otherwise, having a working machine on site is enough.

Which Way Most Businesses Lean

Run a skid steer daily across multiple job sites for years, and a loan usually fits. If your equipment needs to shift with the season, or you don’t want to get stuck holding an aging machine, a lease usually fits better.

Get the call wrong and it’s rarely a disaster. You end up paying for flexibility you didn’t need, or owning a machine you were ready to trade in.

Building a Payment Around the Job, Not the Sticker Price

Your skid steer earns its cost back by being on the job site, not sitting in a lot while you save up for it. The faster it’s working, the sooner the payment stops feeling like a cost and starts looking like the reason the job got done.

If your business is weighing a new or used skid steer purchase, Dimension Funding can walk through what a loan or a lease would look like for that specific machine and timeline. Reach out and talk through the numbers before you commit to either one.

Frequently Asked Questions

Can I finance a used skid steer, or only new units?

Most equipment lenders finance both. The used market moves enough volume that it’s a normal way to buy, not a consolation prize. The Case CE SV280B alone accounted for 533 financed units in early 2026. Used equipment loans typically run shorter terms than new ones too, since there’s less life left on the machine to finance.

What credit score do I need for skid steer financing?

There’s no single score that guarantees approval. Lenders weigh your business history alongside personal credit rather than applying a hard cutoff. On amounts up to $500,000, Dimension Funding can often make that call from your application alone.

How long are typical skid steer loan or lease terms?

Terms commonly run up to 60 months. The actual length depends on whether your equipment is new or used, and how long you plan to keep it. Stretch the term out and your monthly payment drops, but you keep paying longer, so match it to how much life is left in the machine.

Is leasing a skid steer better than buying if I only need it seasonally?

Leasing tends to fit seasonal work better. You’re not stuck holding equipment that sits idle for months at a stretch. A loan makes more sense when the same machine sees steady use all year.

Do skid steer attachments get financed together with the machine?

Usually, yes. Lenders roll attachments you buy alongside the skid steer into the total financed amount, since the payment covers the full equipment cost, not the base machine alone. Confirm this with your lender before the purchase closes, since not every lender handles it the same way.

What happens at the end of a skid steer lease?

It depends mostly on how many hours the machine has on it by then. If it’s still got plenty left in it, buying it at the price set when your lease began often makes the most sense. If it’s worn down, or a newer model would move the job along faster, handing it back or stepping into something newer usually wins out.

How fast can skid steer financing be approved?

Approval can happen the same day when you handle the application and signatures electronically. That speed matters more with used equipment especially, since a specific used unit won’t necessarily still be sitting there next week.

Renewal Financing: Turning Subscription Renewals Into a Retention Mechanic

Renewal Financing: Turning Subscription Renewals Into a Retention Mechanic

Renewal Financing: Turning Subscription Renewals Into a Retention Mechanic

A subscription renewal invoice arrives on a schedule the vendor sets, not the customer’s budget cycle, and that mismatch can be enough on its own to cost a vendor a renewal that had nothing to do with the product. Dimension Funding finances the renewal itself, not just the original purchase, converting the annual or multi-year invoice into a fixed monthly payment while paying the vendor in full at signing.

The same structure applies here as with a new software deployment: subscription fees, implementation, and third-party services bundled into one payment, with application-only approval available up to $500,000 and no financial statements required. For a vendor whose renewal conversation keeps stalling on price rather than product fit, that’s the lever that changes the outcome.

Why a Renewal Date Becomes a Churn Event

The SaaS market is on track to grow from $464.7 billion to $530.0 billion this year alone, on its way to $1.1 trillion by 2033. A renewal lost to invoice timing rather than dissatisfaction disappears from that growth curve for a reason that had nothing to do with the product it was attached to.

The Federal Reserve’s 2024 Small Business Credit Survey found that 56% of employer firms cited paying operating expenses as a financial challenge, with 51% citing uneven cash flow. A renewal invoice landing against that backdrop is competing with payroll and fixed costs for the same limited cash, and a vendor offering only a lump-sum renewal is asking the customer to solve that timing problem unassisted, on a deadline the vendor set.

What Dimension Funding Finances at Renewal

Renewal financing through Dimension Funding covers more than the base subscription line:

  • Annual and multi-year SaaS renewals, spread across monthly payments matched to the actual renewal term rather than billed as a lump sum
  • ERP and CRM platform renewals, the category carrying the largest per-invoice cost inside a U.S. software publishing industry that’s grown to $583.9 billion in 2026 
  • Added seats or modules introduced at renewal, folded into the same monthly payment as the base subscription rather than invoiced separately
  • Multiple renewals due in the same quarter, combined into a single financed transaction when a customer runs more than one platform through the same vendor relationship

A business renewing a $60,000 ERP platform and a $15,000 CRM add-on in the same billing window doesn’t need two separate financing conversations. Structured as one combined request under Dimension Funding’s SaaS financing program, it clears one underwriting event instead of two. Application-only financing remains available up to $750,000 in many cases, so a combined request that exceeds the standard $500,000 software ceiling doesn’t automatically require a full financial-statement review, though deals above $750,000 do. 

Timing the Conversation Before the Invoice Lands

Dimension Funding structures renewals fastest when the conversation starts at the account review stage, before the invoice has gone out and before a customer’s own budget cycle has forced a decision either way.

Dimension Funding’s 90-day deferred payment program extends that runway further: a qualifying customer renews, keeps the platform running without interruption, and owes no payment for the first 90 days. For a renewal date that lands ahead of a customer’s own fiscal cycle, that gap alone can prevent a non-renewal caused purely by the invoice date falling before the customer’s own budget cycle allowed for it.

Multi-year renewals carry a second advantage worth raising in the same conversation. Locking a customer into a longer subscription term at renewal typically secures a lower per-year price than a repeated annual renewal would, and financing that multi-year commitment removes the objection that would otherwise keep a customer on the shorter, more expensive cycle. That makes the case for a three-year renewal easier to make, since the larger commitment doesn’t require a larger payment up front. 

Zero Percent Financing as a Renewal-Specific Lever

Zero percent financing works better at renewal than at initial sale, since the decision at that point is close to a pure price-and-timing question rather than a feature comparison against a competing platform. Structured directly through Dimension Funding’s vendor partner program as a vendor-sponsored offer, it gives a customer a reason to renew on current terms instead of shopping the category during exactly the moment they’re reconsidering the relationship.

It works best scoped narrowly. Applying it across an entire renewal book erodes margin on accounts that were never at risk. Applying it to platform tiers or specific accounts flagged as renewal risks keeps it available where it actually changes the outcome. The vendor absorbs the program’s cost as a customer acquisition and retention expense rather than a financing charge, since Dimension Funding is still paid the full renewal amount at signing regardless of the zero percent terms extended to the customer. 

Building Renewal Financing Into the Account Cycle

A vendor partnership builds renewal financing into account management so it surfaces automatically ahead of every renewal date, rather than depending on whichever account manager happens to raise it. Running a specific renewal amount through Dimension Funding’s payment calculator ahead of the call gives an account manager an exact monthly figure to bring to the customer, rather than a vague reference to “financing options” the customer then has to ask about.

For a vendor whose renewal book runs across dozens or hundreds of accounts, the application-only thresholds aren’t the ceiling to watch: Dimension Funding’s total financing capacity extends past $10 million. Section 179 is worth mentioning where relevant, since qualifying software falls under the 2026 deduction limit of $2,560,000, phasing out above $4,090,000, though the customer’s own accountant should confirm how it applies to a specific renewal. Dimension Funding has run vendor financing programs long enough to have seen most versions of this conversation, detailed on the About Us page for vendors sizing up a long-term partner rather than a one-off transaction.

Making the Renewal Date Work for Retention

A renewal date doesn’t have to put an account at risk. Spreading the invoice into a monthly payment matched to the subscription term keeps the account in place through the exact point it would otherwise get re-evaluated against every other line item competing for that budget.

Contact Dimension Funding to build renewal financing into a specific subscription book, or to set up a standing vendor partnership ahead of the next renewal cycle.

Frequently Asked Questions

Can a renewal be financed if the original subscription purchase was paid in cash rather than financed?

Yes. Renewal financing through Dimension Funding doesn’t depend on how the original term was paid for. A customer who paid the first year in cash can still finance the renewal on its own terms, since each renewal is underwritten independently of how the previous term was paid. 

Does financing a multi-year renewal require the customer to commit to the full term upfront?

The customer commits to the subscription term as they would with any multi-year renewal. Dimension Funding underwrites the full term at signing, so a vendor gets paid the complete renewal value upfront even though the customer’s payment obligation runs monthly across multiple years. 

Can seats or modules added at renewal be financed alongside the base subscription?

Yes, provided the added seats or modules are priced and included in the renewal invoice submitted with the application. Pricing finalized after the underwriting decision typically requires a separate add-on request rather than being folded into the original approval. 

How does combining multiple renewals into one financed transaction affect the application-only threshold?

The combined total across all renewals in a single request counts toward the $500,000 application-only ceiling. This applies when all renewals run through the same vendor relationship; if a customer is renewing platforms from two unrelated vendors, each is submitted as its own request even if the invoices land in the same quarter. 

Does a renewal financed at a lower multi-year price lock that price in for the full term?

Yes, in the sense that the payment amount is fixed once the financing agreement is signed. The multi-year pricing itself is set by the vendor’s contract terms, not by Dimension Funding, but financing that fixed price avoids the repricing that typically comes with repeated annual renewals. If the vendor’s contract includes a built-in price increase partway through the term, the monthly payment is set at signing based on that schedule rather than renegotiated when the increase takes effect. 

Is renewal financing available for a downgraded or reduced-scope renewal?

Yes. A renewal that reduces seat count or scope compared to the prior term can still be financed, based on the actual renewal invoice rather than the original contract value.

What happens if a renewal financing request doesn’t clear at standard terms?

Restructuring the request, whether by separating add-on modules into their own agreement, adjusting the term length, or starting the conversation earlier in the renewal cycle, resolves most declines that looked final on the first attempt. Most restructures are handled as an amendment to the existing application rather than a new submission, which keeps the original review timeline instead of restarting it.