Some business owners want financing that adapts and flexes with every fluctuation in cash flow. Others want the opposite: a number they can circle on the calendar and a payment that never changes between now and then. A working capital term loan is built for the second kind of business owner, one who values certainty over flexibility.
Dimension Funding has spent over 40 years financing small and mid-sized businesses across the U.S., and its working capital loans are structured around exactly that kind of predictability. Contact Dimension Funding to see if a fixed structure fits your business, or keep reading to understand how it actually works.
What Makes a Term Loan “Fixed”
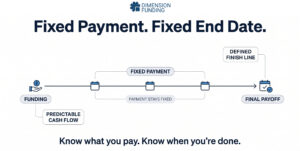
A working capital term loan disburses a lump sum upfront and sets a fixed repayment schedule from day one. The payment amount, the total financing cost, and the final payoff date are all established at the start of the loan and don’t move, regardless of how the business performs during the term.
This is fundamentally different from revolving financing, where the balance and the payment can shift depending on how much is drawn and repaid. With a term loan, there’s no guessing at what next month’s payment will be. The number on the schedule today is the same number six months or a year from now.
What Your Payment Is Actually Made Of
One of the biggest misconceptions about a fixed-payment working capital term loan is that every payment reduces the loan balance by the same amount. In reality, while your payment amount stays the same throughout the loan, how that payment is allocated changes over time. Early payments cover a larger share of financing cost and a smaller share of principal, because the outstanding balance is at its highest early in the term.
Payment Period | Financing Cost Portion | Principal Portion |
Early in term | Higher | Lower |
Middle of term | Moderate | Moderate |
Late in term | Lower | Higher |
This process is known as amortization. The Consumer Financial Protection Bureau’s explanation of how loan paydown works notes that in an amortizing loan, a greater percentage of each payment goes toward financing cost early in the term, while a greater percentage goes toward principal as the term progresses, which is also why a longer loan term lowers the payment amount but increases the total financing cost paid over the life of the loan.
For business owners, understanding this structure makes it easier to track progress toward becoming debt-free: the monthly payment never changes, but each payment reduces the remaining balance by a larger amount than the one before it, so the loan balance declines more quickly in the later stages of repayment.
Why a Fixed Payment Matters for Budgeting
Predictability has real value beyond peace of mind. When a business knows its exact loan payment months in advance, it can build that number directly into cash flow projections without leaving room for surprises. That certainty makes it easier to plan payroll, inventory purchases, and other recurring expenses around a known obligation.
This is especially valuable compared to financing tied to sales volume, like a merchant cash advance, where the amount withdrawn each day shifts with revenue. A slow sales month with a merchant cash advance still pulls a percentage of whatever comes in, but a fixed-payment term loan stays exactly the same, which can actually make a slow month easier to manage rather than harder.
Why a Fixed End Date Matters Just as Much
A fixed end date gives a business a clear finish line. There’s no ambiguity about when the obligation will be paid off, which makes it far easier to plan around, whether that means budgeting for when cash flow frees up or timing a future financing need around the loan’s payoff.
Dimension Funding’s working capital loans run on terms up to 24 months, giving businesses a defined window rather than an open-ended obligation. Knowing exactly when a loan closes out, down to the month, removes one more variable from long-term financial planning.
How Repayment Frequency Fits Into a Fixed Structure
Even within a fixed-payment, fixed-term loan, businesses have some control over how that structure is scheduled. Repayment can typically be set up weekly, daily, or monthly, depending on which cadence best matches the business’s revenue pattern, without changing the fact that the total payment and payoff date remain fixed.
A seasonal business might prefer weekly payments that ease pressure during slower months, while a business with steady daily transactions might choose daily repayment to match its cash flow rhythm. Regardless of the schedule chosen, the fixed nature of the loan means the borrower always knows the total obligation and when it ends.
Qualifying for a Fixed-Payment Term Loan
Approval for a working capital term loan generally comes down to a handful of core requirements: annual revenue above a set threshold, majority ownership documentation, and recent bank statements to establish cash flow history. Larger loan requests typically require additional documentation, such as corporate tax returns.
Many lenders, including Dimension Funding, use a single-page application supported by bank statements rather than a lengthy financial statement package, which keeps the process fast without sacrificing the fixed structure borrowers are choosing this loan type for. Because underwriting reviews cash flow directly, businesses without extensive collateral or years of credit history can still qualify for predictable, fixed terms.
Fixed Term Loans vs. Variable-Cost Alternatives
The clearest way to see the value of a fixed structure is to compare it against financing where the cost moves with the business. A merchant cash advance, for example, ties repayment to a percentage of daily sales, which means the total cost and repayment timeline can both shift depending on how the business performs.
Businesses that compare the two often find that a fixed-payment working capital loan can cost considerably less than a merchant cash advance, since the payment amount and end date stay locked in regardless of sales fluctuations. That stability is often worth more to a business than the theoretical upside of a variable structure that could, in a strong sales month, cost less, since it can also cost significantly more in a weak one.
When a Fixed Term Loan Is the Right Fit
A fixed-payment, fixed-end-date loan works best for a defined, one-time need: covering a known expense, bridging a specific cash flow gap, or funding a project with a clear scope. Because the loan amount and schedule are set upfront, it’s less suited to a business that expects to need repeated access to capital over time.
For recurring or unpredictable capital needs, a revolving line of credit may be a better match, since it allows repeated draws rather than a single lump sum. The right choice comes down to whether your business needs one clearly bounded loan or ongoing, flexible access to funds.
Certainty You Can Plan Around
A working capital term loan offers something a lot of financing options can’t: total certainty about what you’ll pay and when you’ll be done paying it. That fixed payment and fixed end date make it easier to plan every other part of the business around one known obligation. Dimension Funding offers working capital loans between $25,000 and $250,000, with terms up to 24 months and same-day or next-business-day funding. Contact Dimension Funding to find out what your business qualifies for.
If my business’s cash flow improves, can I pay off a fixed term loan early?
Many lenders allow early payoff, though it’s worth confirming whether there’s any early payoff provision before signing. The CFPB’s general guidance on loan terms notes that some lenders include prepayment penalties that offset part of the savings from paying early, so reviewing the loan agreement’s prepayment language before signing, rather than after, is the more reliable way to know what an early payoff would actually save.
Does a fixed term loan report to business credit bureaus the same way a line of credit does?
Generally, yes. Most term loans and lines of credit are both reported to business credit bureaus, though the specifics depend on the individual lender’s reporting practices. It’s worth confirming with any lender before assuming either product affects credit reporting differently.
Can I request a second term loan while still repaying a current one?
It depends on the lender’s underwriting and how much of the current loan remains outstanding. Some businesses qualify for an additional loan based on updated cash flow, while others may need to wait until the existing balance is further paid down.
What happens if a payment is missed on a fixed term loan?
Policies vary by lender, but a missed payment typically triggers a grace period before late fees or other consequences apply. Contacting the lender proactively if a payment is going to be late is generally more productive than letting it pass without notice.
Is a fixed term loan reported differently depending on the repayment frequency I choose?
No. Whether repayment is scheduled weekly, daily, or monthly, the loan itself is still reported as a single fixed obligation. The repayment cadence affects cash flow timing, not how the loan appears on a credit report.
Can the loan amount be adjusted after the term loan has already funded?
Typically not without a separate application. Since the amount, schedule, and payoff date are all fixed at origination, a business that needs more capital after funding usually applies for additional financing rather than modifying the existing loan.
Does a fixed term loan make sense for a business that’s just starting to build credit history?
It can, since many working capital lenders weigh recent cash flow and bank statement history more heavily than an extensive credit record. A newer business with strong, consistent revenue may still qualify even without years of established credit.