What Shapes Approval on a Working Capital Loan

working capital loans interest rates

What Shapes Approval on a Working Capital Loan

Two businesses can apply for the same working capital loan amount and end up with very different terms. The difference usually isn’t luck, it’s a handful of specific factors that lenders weigh every time they evaluate an application. Knowing what those factors are gives you real leverage before you ever submit one.

Dimension Funding has spent over 40 years financing small and mid-sized businesses across the U.S., and its working capital program is built around evaluating a business’s full financial profile rather than a single number. Contact Dimension Funding to talk through your business’s profile before applying, or keep reading to understand what underwriters actually look at.
What-Shapes-Approval-on-a-Working-Capital-Loan

How Underwriters Build a Risk Profile

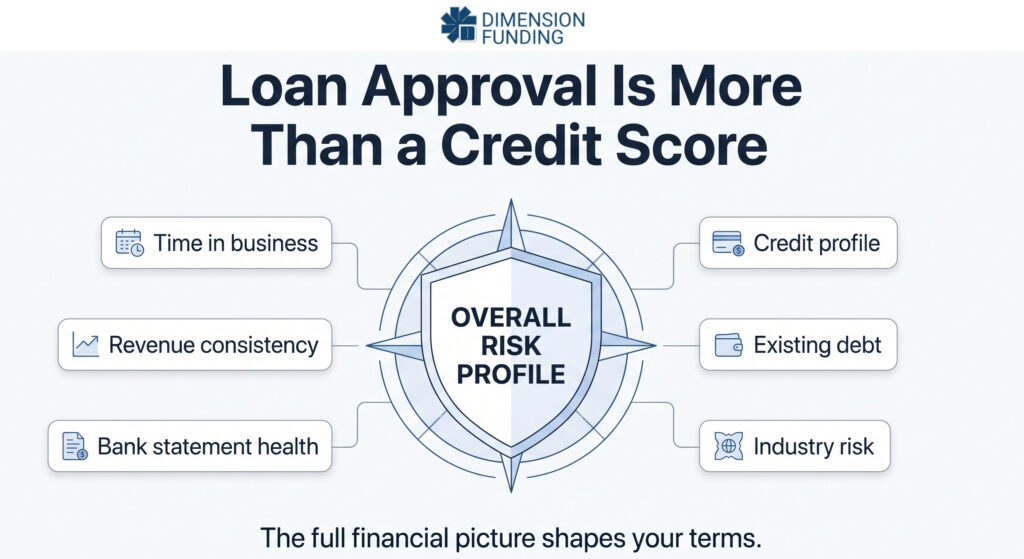
Working capital loan approval is rarely based on a single number. Instead, underwriters combine several financial indicators to build a comprehensive risk profile that helps determine how likely a business is to repay on schedule. This holistic approach reflects federal banking guidance that prudent underwriting should consider a borrower’s overall financial condition, repayment capacity, and cash flow, not just one metric in isolation. The Office of the Comptroller of the Currency’s Commercial Loans booklet explains that sound commercial lending decisions rely on evaluating multiple sources of financial information before extending credit, rather than defaulting to a single ratio or score as a stand-in for the full picture.

Underwriting Factor

What It Tells the Lender

Time in business

Demonstrates business stability and operating history

Revenue consistency

Indicates predictable cash flow available for repayment

Bank statement trends

Reveals day-to-day cash management and liquidity

Credit history

Shows past borrowing and repayment behavior

Existing debt

Measures current repayment obligations and financial leverage

Industry risk

Reflects exposure to economic cycles and sector-specific challenges

Rather than assigning equal weight to every factor, lenders evaluate how they interact. A business with only two years of operating history may still receive favorable terms if it shows consistent monthly deposits, healthy account balances, and a manageable debt load. A long-established business, on the other hand, may see less favorable terms if recent bank statements reveal frequent overdrafts or declining revenue, which is why the sections below break down each factor individually.

Time in Business Sets the Baseline

Lenders view a longer operating history as evidence that a business can weather slow periods and still make payments. A company with five or ten years of consistent revenue is a more predictable applicant than one that opened its doors last year, and that predictability typically translates into more favorable terms.

Newer businesses aren’t necessarily locked out, but they often see more conservative terms until they build a longer track record. If your business is still young, strong recent revenue and clean bank statements can help offset the limited history in a lender’s eyes.

Revenue Consistency Matters More Than Revenue Size

A lender evaluating a working capital loan cares less about how much a business makes and more about how reliably that revenue shows up month after month. Steady, predictable deposits signal that a business can absorb a fixed payment without strain, which tends to support more favorable terms.

Erratic revenue, with big months followed by lean ones, reads as risk even if the annual total is strong. Businesses with seasonal swings can still qualify for competitive terms, but it often takes a documented pattern of managing those swings well over time.

Bank Statement Health Drives the Underwriting Conversation

Underwriters look closely at average daily balance, negative balance days, and overdraft frequency when evaluating an application. A business that consistently carries a healthy balance and avoids overdrafts is demonstrating exactly the kind of cash management a lender wants to see before extending credit.

Frequent negative balances or NSF fees push the underwriting conversation in the other direction, since they suggest a business may already be operating close to the edge of its cash flow. Cleaning up account activity in the months before applying can meaningfully improve the terms a lender is willing to offer.

Credit Profile Still Plays a Role

Personal and business credit history factor into approval, but rarely in isolation. A working capital lender weighs credit alongside cash flow, so a lower credit score doesn’t automatically rule out favorable terms if the underlying bank statements are strong.

That said, a stronger credit profile generally opens the door to better terms and, in some cases, higher approved amounts. Businesses considering an application benefit from checking their credit standing beforehand so there are no surprises once underwriting begins.

Industry Risk Adds Context to the Rest

Industry is the one factor on the list that has nothing to do with a specific business’s own numbers, and everything to do with where that business sits inside a larger economic pattern. A restaurant, a construction subcontractor, and a medical practice can each show identical revenue and identical bank statement health, and still receive different terms, because lenders track how exposed each industry tends to be to seasonal swings, supply shocks, or broader economic downturns.

That doesn’t mean a business in a higher-risk industry is worse off across the board. It means the other factors on this list carry a bit more weight in that evaluation. A seasonal landscaping business that can show it’s managed its slow months well for several years in a row is demonstrating exactly the kind of resilience a lender is trying to price for, which can offset the industry classification rather than being overridden by it.

Loan Amount and Term Length Shape the Terms You’re Offered

Larger loan amounts and longer terms typically carry more risk for a lender, since more capital is outstanding for a longer stretch of time. That added exposure is often reflected in the terms offered, particularly once a request crosses thresholds that require deeper documentation.

Dimension Funding’s working capital loans range from $25,000 to $250,000 with terms up to 24 months, and requests over $100,000 generally require corporate tax returns in addition to bank statements. Matching your requested amount and term to your actual need, rather than borrowing more or longer than necessary, keeps the overall terms as favorable as possible.

Repayment Structure Influences the Terms You’re Offered

The frequency of your repayment plan affects how a lender views risk over the life of the loan. Daily and weekly repayment plans return capital to the lender faster and more often, which can support more favorable terms compared to a monthly schedule stretched over a longer period.

Monthly repayment plans typically require a stronger credit profile and are capped at shorter terms, since a lender is collecting less frequently and carrying more exposure between payments. Choosing the repayment cadence that best matches your revenue pattern isn’t just about convenience, it can directly affect the terms on your offer.

How a Fixed Payment Compares to Alternative Financing Costs

One of the clearest ways to see what shapes overall cost is comparing a fixed-payment working capital loan to a merchant cash advance. A merchant cash advance ties repayment to a percentage of daily sales, which means the total cost can swing significantly depending on how the business performs during the repayment period.

Businesses that compare this type of financing often find that a fixed-payment working capital loan can cost considerably less than a merchant cash advance, since the payment stays the same regardless of sales volume. That predictability is part of why a strong financial profile paired with a fixed-payment loan usually ends up costing less over time than a variable-cost alternative.

Putting the Pieces Together Before You Apply

Your working capital loan terms aren’t decided by a single number, they’re shaped by time in business, revenue consistency, bank statement health, credit profile, industry, loan size, and repayment structure working together. None of these factors operate in a vacuum, and a weaker showing on one can often be offset by strength in another, which is exactly why two businesses with the same revenue can walk away from the same lender with different terms.

Dimension Funding offers working capital loans between $25,000 and $250,000, with same-day or next-business-day funding and a single-page, bank-statement-based application. Contact Dimension Funding to see what your business qualifies for.

If two businesses have identical revenue, will they always get the same terms?

Not necessarily. Revenue is only one input, and underwriters also weigh consistency, bank statement health, credit history, and existing debt. Two businesses with the same top-line revenue can look very different once those other factors are layered in.

Does switching business bank accounts right before applying hurt an application?

It can complicate underwriting, since lenders typically want to see several months of consistent history at one institution to establish a reliable pattern. A recent account switch may mean providing statements from both accounts or waiting until the new account has enough history.

Can a business improve its standing in the months before applying?

Yes. Paying down existing debt, avoiding overdrafts, and maintaining steady deposit patterns for a few months before applying can meaningfully strengthen how an application is viewed, even without changing the business’s underlying revenue.

Does the industry a business operates in affect approval beyond just its financials?

It can. Lenders sometimes factor in how exposed a given industry is to economic cycles or seasonal disruption, which means two businesses with similar financials in different industries may be evaluated somewhat differently. A business that can document how it’s managed seasonal or cyclical exposure well in the past often narrows that gap.

Is it better to apply for a smaller amount to improve approval odds?

Not automatically. Requesting less than the business actually needs can lead to a second financing need later, so it’s generally better to request an amount that matches the real gap and let the underwriting process weigh in on fit, rather than under-requesting preemptively.

How far back do lenders typically look at bank statement history?

Most working capital lenders review three to six months of statements, though larger requests may prompt a longer look-back or a request for additional documentation to confirm the pattern holds over time.

Can an existing customer get updated terms without reapplying from scratch?

Many lenders, including Dimension Funding, can reassess an existing customer’s terms based on updated bank statements and revenue rather than requiring a full new application, particularly if the business’s financial profile has improved since the original loan.

When a Vendor Financing Deal Gets Declined: Second-Look Options

When a Vendor Financing Deal Gets Declined: Second-Look Options

When a Vendor Financing Deal Gets Declined: Second-Look Options

A declined financing application doesn’t necessarily mean a sale is lost. More often it just means the deal didn’t fit the box it was put in, not that the buyer can’t get financed.

Dimension Funding works with credit profiles ranging from strong Tier A commercial credit down to marginal credit, and application-only financing, meaning no financial statements required, covers equipment purchases up to $250,000 and combined equipment-plus-software deals up to $500,000. That kind of range is exactly why a decline at one tier isn’t the end of the conversation.

Industry-wide, roughly one in five equipment finance applications don’t clear on a first pass: the Equipment Leasing & Finance Association’s CapEx Finance Index showed the industry-wide credit approval rate at 79.5% in June 2026, approaching an all-time high. For a vendor selling regularly, that means declines are routine, and how a vendor handles them shapes how many of those buyers eventually close.

Why Financing Applications Get Declined

Most declines trace back to a small set of factors: credit history, time in business, and how a buyer’s existing debt load and cash flow look on paper. The Federal Reserve’s Small Business Credit Survey found that while 41% of applicants received all the financing they sought, 36% received just some, and 24% received none, with firms increasingly likely to say they were denied because they already had too much debt. 

A Decline Isn’t Necessarily Final

A decline at the standard equipment-only tier doesn’t automatically apply to every structure a buyer could submit. Adding software, implementation costs, or a service contract to the same transaction shifts it into the combined threshold, which runs up to $500,000 without financial statements. A buyer whose equipment-only request stalled at $260,000 may fit comfortably once the software component that was going to be purchased separately gets combined into the same financing application.

Deal size is also worth revisiting before assuming a decline is permanent. Application-only financing remains available up to $750,000 in many cases, with transactions above that requiring basic financials rather than a full bank-style underwriting cycle. A buyer initially structured for a larger purchase may qualify cleanly once the request is scoped to what they need on day one, with a second phase financed separately later. Running the numbers through Dimension Funding’s payment calculator before resubmitting removes the guesswork and gives a vendor a realistic monthly figure to present to the buyer.

Restructuring Before Resubmitting

What tends to move a declined deal forward is a change to the structure itself:

  • Extending the term to lower the monthly payment relative to the buyer’s cash flow, rather than keeping the original repayment schedule fixed
  • Narrowing the equipment list to what the buyer needs immediately, with additional items financed as a second phase later
  • Separating software from hardware into distinct applications, since bundling assets with very different useful lives can work against a combined request
  • Financing a software renewal on its own terms, built around the contract length rather than treated as a lump-sum expense alongside physical equipment
  • Pulling the service or maintenance contract out on its own, financed as a standalone agreement matched to the contract’s length rather than bundled into the equipment or software term 

For a vendor whose buyer got declined on a combined hardware-and-software request, splitting the two into separate applications is often a faster path than waiting on the original one. Dimension Funding finances software renewals and multi-year licensing agreements under software renewal terms structured around the contract itself, which changes how a buyer’s obligations look on paper compared to a single bundled request. 

A multi-year support or maintenance contract attached to a declined deal doesn’t have to move with the rest of the transaction. Dimension Funding can finance that contract on its own, matched to the service term rather than the equipment it supports. That’s a smaller, more targeted request than resubmitting the full package, and easier to qualify for since it’s evaluated against a smaller total. 

Working Capital as a Fallback Structure

Not every declined equipment or software request needs to be resubmitted as equipment or software financing. Dimension Funding’s working capital loans run from $25,000 to $250,000 for businesses with annual revenue above $150,000, structured around the business’s cash flow rather than a specific asset purchase. For a buyer whose equipment application stalled because the collateral didn’t fully support the request, a working capital structure evaluated on revenue and bank statements instead can sometimes get to “yes” where an asset-based application couldn’t.

It isn’t a universal substitute, and the decline reason should drive whether it’s worth raising. A decline tied to collateral, where the equipment itself didn’t fully support the request, rarely resolves through a working capital structure, since the same buyer still has to qualify on cash flow alone. 

Zero Percent Financing and the 90-Day Deferral

For vendors selling software or higher-margin equipment lines, a zero percent financing offer can reopen a deal that stalled on price sensitivity rather than credit. Structured directly through Dimension Funding as a vendor-sponsored program, it gives a buyer another reason to move forward on the same purchase price rather than shopping the deal to a competitor. Vendors interested in setting one up can start with the vendor partner application, which also sets up a standing second-look process instead of handling declines one at a time. 

A 90-day deferral works differently: a qualifying buyer can take delivery of equipment or software, put it to use, and not owe a first payment for 90 days. For a buyer waiting on their own incoming revenue or a budget cycle to open up, that runway alone sometimes resolves what looked like a decline-worthy cash flow gap on the original application.

What a Second Look Means for a Vendor’s Close Rate

A vendor that treats every decline as final is walking away from deals a different structure would have closed. Following up with a revised application, a working capital alternative, or a deferral option gets more out of the same pipeline without spending a dollar more to generate it. Dimension Funding has run vendor financing programs for more than four decades, and sales teams that build a second-look habit into their process tend to see it pay off across more of their pipeline than a one-and-done application approach ever will. 

Section 179 applies the same way to a restructured deal as it did to the original one, and a buyer weighing a shorter term against a smaller current-year deduction sometimes needs that tradeoff spelled out before deciding whether to keep pushing. 

Turning a Decline Into a Structured Follow-Up

A declined application is information about the deal as submitted, not a verdict on the buyer. Reworking the structure, the deal size, or the documentation attached to it is usually a shorter path back to yes than starting over somewhere else. Contact Dimension Funding to talk through what a specific declined deal would look like restructured, or to set up a standing process for handling declines as part of an ongoing vendor partnership.

Frequently Asked Questions

Does a decline on an equipment-only application affect how a combined equipment-and-software resubmission is reviewed?

No. Each structure is evaluated on its own terms. A buyer declined at the $250,000 equipment-only tier can be resubmitted under the combined threshold, which runs up to $500,000, without the earlier decision carrying over.

Can a vendor resubmit a declined application without the buyer starting the paperwork over from scratch?

In most cases, yes. The original application details can carry into a restructured resubmission, since the underlying business information typically hasn’t changed, only the deal structure being proposed.

Does a partial approval count as a decline for restructuring purposes? 

No. A partial approval, where a buyer is cleared for less than the original request, is a different outcome than a decline and doesn’t require the same restructuring approach. In that case, the buyer can choose to move forward at the approved amount, cover the difference with a down payment, or revisit the request using the same restructuring options that apply to a full decline. 

Can a co-signer or guarantor change the outcome on a declined application?

Adding a qualified guarantor can strengthen an application where the original decline was tied to the primary applicant’s credit profile specifically. It’s most useful when the business itself has reasonable revenue but the ownership’s personal credit was the limiting factor.

Does financing a trade-in as part of the deal affect approval odds on a resubmission?

It can help. Applying a trade-in’s value toward the purchase reduces the total amount being financed, which sometimes moves a deal back under an application-only threshold it had previously exceeded.

If a buyer’s deal gets declined, does that affect the vendor’s own standing in the vendor partnership?

No. Approval decisions are tied to the buyer’s application, not the vendor’s account. A vendor’s partnership terms and access to financing tools for other customers aren’t affected by an individual buyer’s outcome.

Can a declined software subscription financing request be restructured as a shorter-term agreement instead?

Yes. A multi-year subscription request that gets declined can sometimes be resubmitted as financing tied to a single renewal term instead, which changes the total obligation being evaluated without changing what the buyer is purchasing.

Box Truck Financing: Delivery Vehicle Loans for Small Business Fleets

Box Truck Financing: Delivery Vehicle Loans for Small Business Fleets

Box Truck Financing: Delivery Vehicle Loans for Small Business Fleets

The last-mile delivery economy runs on box trucks — and for most operators, those trucks are financed. U.S. domestic parcel volume hit 23.9 billion packages in 2025, with independent carriers growing 13% year-over-year, the fastest of any segment, according to ShipMatrix’s 2025 U.S. Parcel Market Report. The global last-mile delivery market is projected to reach $277.76 billion by 2030, per The Business Research Company.

Dimension Funding has been a vendor partner to construction and cargo companies for decades, financing new and used box trucks for small and medium-sized businesses across the country. With same-day approvals and an A+ BBB rating, box truck financing through Dimension Funding includes no payments for 90 days on qualifying transactions, fixed rates for the life of the loan, and terms up to 60 months.

How Much Does a Box Truck Cost in 2026?

New medium-duty box trucks — Class 4 through Class 6 vehicles used for most delivery and moving operations — typically run $45,000 to $100,000 depending on body length, lift gate configuration, and manufacturer. Refrigerated or specialty units run higher.

Used box trucks in good working condition generally fall between $25,000 and $60,000, with late-model used units commanding more. Most businesses launching a delivery operation or adding a fleet unit budget $40,000 to $80,000 as a realistic all-in acquisition target.

New vs. used: what changes in financing

New box trucks qualify for the longest loan terms and carry manufacturer warranties that reduce maintenance risk during the financing period. Used trucks cost significantly less upfront — making them the entry point of choice for Amazon DSP contractors, local delivery startups, and operators expanding a fleet without tying up large amounts of capital.

Both new and used box trucks qualify for Section 179 and 100% bonus depreciation under current IRS rules, per IRS Publication 946, provided the asset is placed in service during the tax year.

Financing Options for Box Truck Operators

The right structure depends on whether you’re acquiring a single truck, building a fleet, or managing working capital alongside vehicle payments.

Equipment financing

Equipment financing is the most common and accessible path for box truck acquisition. The truck itself serves as collateral, improving approval odds compared to unsecured business lending — particularly for newer operations. Dimension Funding offers terms up to 60 months, 100% financing on qualifying transactions, and application-only decisions up to $250,000 with no financial statements required.

SBA loans

SBA loan programs — particularly the 7(a) — suit established operators who need larger financing amounts for multi-truck purchases or fleet buildouts. SBA loans involve more documentation and a longer approval timeline than equipment-specific financing but offer longer repayment terms for larger capital needs.

Working capital loans

For operators who already have trucks running but need funds to cover payroll, fuel, insurance, or a gap between delivery contracts, a working capital loan provides flexible short-term capital. Dimension Funding offers working capital loans with terms up to 24 months and daily, weekly, or monthly repayment options.

What Lenders Look at for Box Truck Applications

Delivery contracts and route stability are strong positive signals. A business with a documented Amazon DSP agreement, a FedEx contractor arrangement, or a consistent roster of commercial delivery clients demonstrates predictable revenue that lenders value when underwriting a payment-dependent asset. 

The average American household received 167 packages in 2024, according to Capital One Shopping’s parcel delivery research — and U.S. parcel revenue is projected to reach $286 billion by 2028, meaning the underlying demand that drives box truck utilization isn’t going anywhere.

Time in business and credit profile

Established operators with two or more years of history are in the strongest approval position. According to the Federal Reserve’s 2025 Small Business Credit Survey, businesses under two years had a full-funding rate of 28% compared to 57% for businesses with ten or more years of history. Equipment financing partially offsets this because the truck as collateral reduces lender exposure.

Down payments

Borrowers with strong credit may qualify for low or no down payment financing on qualifying transactions. Newer businesses or thinner credit profiles should budget 10–20% down. Higher down payments reduce monthly payment size and improve approval odds when business history is limited.

Scaling from One Truck to a Fleet

A single box truck can generate strong revenue on consistent routes, but the business model becomes more defensible with multiple units. Fleet operators spread fixed costs across more revenue-generating assets — improving margin per truck as the fleet grows.

The key constraint is usually cash flow. Adding a second or third truck before the first is generating consistent net income is a common way to overextend. Operators building toward a larger fleet benefit from establishing strong payment history on initial financing before scaling — consistent on-time payments improve the credit profile that underlies subsequent approvals.

Structuring multi-unit financing

Dimension Funding can finance multiple trucks under a single structure or as separate transactions depending on deal size and business profile. For fleets requiring more than $250,000 in total financing, financial statements will typically be required.

The Operating Economics of a Delivery Box Truck

A box truck running local or regional delivery routes generates revenue through per-stop delivery contracts, daily or weekly route rates, or hourly moving jobs. Operating costs include fuel, insurance, maintenance, driver wages where applicable, and dispatch fees.

The American Transportation Research Institute (ATRI) reports total operating costs for commercial trucks averaged $2.26 per mile in 2024. Box trucks operating shorter urban routes with more stops per mile tend to have different cost structures than long-haul equipment — but the principle holds: know your cost structure before committing to a monthly payment.

Break-even planning before you sign

The loan payment is fixed. Revenue isn’t. Before financing a box truck, map out how many delivery stops, moving jobs, or route miles are needed monthly to cover the payment plus fuel, insurance, and maintenance.

This gives you a realistic picture of whether the operation is viable at your current route volume — or what you’d need to build toward to make the numbers work.

Financing Your Box Truck Fleet with Dimension Funding

Dimension Funding finances new and used box trucks for operators across delivery, moving, distribution, and logistics industries. Application-only financing is available up to $250,000 with no financial statements required, and most credit types are accepted — including first-time operators and businesses declined by traditional banks.

Contact Dimension Funding to discuss financing options for your specific truck, fleet size, and business timeline — same-day decisions are available on qualifying transactions.

Frequently Asked Questions

How much do I need to put down on a box truck loan? 

Down payment requirements vary by credit profile and business history. Borrowers with strong credit may qualify for low or no down payment on qualifying transactions. Newer businesses or those with limited credit history typically need 10–20% down. The truck itself serves as collateral, which generally makes equipment financing more accessible than unsecured business loans at comparable down payment levels.

Can I finance a box truck as a startup or new business? 

Yes. Equipment financing is typically more accessible for startups than conventional business loans because the truck reduces lender risk as collateral. Having a delivery contract, a defined client base, or a documented route arrangement strengthens a startup application significantly. Dimension Funding accepts most credit types, including first-time operators.

What types of businesses does box truck financing cover? 

Box truck financing through Dimension Funding covers virtually any commercial delivery or transport application — local and regional delivery, last-mile logistics, Amazon DSP and similar contractor programs, moving and relocation services, medical supply distribution, food service distribution, and more.

Can I finance multiple box trucks at once? 

Yes. Dimension Funding can structure financing for single trucks or multiple units. Application-only financing is available up to $250,000; larger fleet transactions may require financial statements. Operators building a fleet often finance the first unit, establish payment history, then expand — a pattern that strengthens subsequent applications.

Can I write off a financed box truck on my taxes? 

Yes. Section 179 allows businesses to deduct the full purchase price of qualifying equipment placed in service during the tax year — up to $2,560,000 for 2026 per IRS Publication 946. The One Big Beautiful Bill Act of 2025 also restored 100% bonus depreciation for qualifying property placed in service after January 19, 2025, including used equipment new to your business. Consult a tax advisor to confirm eligibility.

What’s the difference between financing and leasing a box truck? 

Financing gives you ownership from day one — you build equity and own the truck at term end. Leasing finances the use of the truck rather than its full value, with lower monthly payments but no ownership at the end. For box trucks in ongoing operations, financing typically offers better long-term economics given the asset’s resale value. Leasing suits operators who prefer to cycle equipment or want lower fixed monthly costs.

How does box truck financing differ from semi truck financing? 

Box trucks are lower-cost assets than Class 8 semis, meaning smaller loan amounts, shorter terms, and less scrutiny around freight contracts or CDL history. Approval is generally more straightforward — lenders focus on delivery contract stability and business cash flow rather than specialized freight market knowledge.

Food Truck Financing in 2026: Startup Loans & Equipment Funding

Food Truck Financing in 2026: Startup Loans & Equipment Funding

Food Truck Financing in 2026: Startup Loans & Equipment Funding

Starting a food truck is one of the more accessible paths into the food service industry — but accessible doesn’t mean cheap. Total startup costs typically range from $50,000 to $250,000 depending on whether you buy new or used, what equipment your menu requires, and what your local permitting environment looks like. Knowing how to finance that investment strategically is what separates operators who launch well-capitalized from those who run out of runway before they find their footing.

Dimension Funding has provided commercial equipment financing for over 40 years, working with food service operators, entrepreneurs, and small business owners to fund truck purchases, kitchen equipment, and startup costs. With same-day approvals, an A+ BBB rating, and decades of experience as a vendor partner to restaurants, food trucks, and the culinary industry, Dimension Funding offers a faster path to funding than most traditional lenders — including food truck financing built around the specific needs of mobile food businesses.

How Big Is the Food Truck Industry in 2026?

Food trucks are no longer a niche concept. The U.S. food truck market is valued at approximately $1.16 billion in 2026 and is projected to reach $1.59 billion by 2031 at a 6.53% CAGR, according to Mordor Intelligence. Approximately 36,000 to 40,000 trucks operate nationwide, with the industry growing 6–8% annually, per PitStop’s 2026 food truck industry data.

The average established food truck generates approximately $346,000 in annual revenue, according to foodtruckprofit.com’s 2026 statistics — and roughly 60% survive three or more years. The ones that fail are almost always undercapitalized, which is what makes proper financing at launch so important.

What Does It Actually Cost to Start a Food Truck?

Before you can finance a food truck, you need a realistic picture of what you’re financing. Startup costs are wider-ranging than most first-time operators expect.

The truck itself is the biggest line item. A new, fully outfitted food truck typically runs $75,000 to $200,000. A used truck can be acquired for $30,000 to $100,000, though budget an additional $5,000 to $15,000 for repairs or retrofits. Kitchen equipment adds $10,000 to $45,000 depending on your menu.

Permits, licensing, and working capital

Permitting costs catch most first-time operators off guard. According to the U.S. Chamber of Commerce Foundation’s Food Truck Nation study, the average food truck operator spends approximately $28,000 on regulatory requirements in the first year — though this varies dramatically by city. 

Working capital to cover the first 60–90 days of operations (food inventory, fuel, commissary fees, insurance) adds another $10,000 to $20,000. Most operators launching a full-time operation should budget a total of $100,000 to $150,000 to cover all costs and maintain an adequate cash buffer.

Financing Options for Food Truck Startups

No single loan type fits every situation. The right financing structure depends on your credit profile, business history, and how much you need to borrow.

Equipment financing

Equipment financing is the most accessible entry point for food truck startups because the truck itself serves as collateral. This reduces lender risk in ways that unsecured loans cannot — and translates directly into easier approval, including for newer businesses. 

Dimension Funding offers equipment financing with terms up to 60 months, 100% financing on qualifying transactions, and application-only decisions up to $250,000 with no financial statements required.

SBA loans

The Small Business Administration’s loan programs — particularly the SBA 7(a) and SBA Microloan — are well-suited for food truck startups that qualify. SBA 7(a) loans can go up to $5 million and offer longer repayment terms than most conventional equipment loans, making monthly payments more manageable for early-stage operators. 

SBA Microloans top out at $50,000 and are specifically designed for early-stage small businesses with limited credit history. The tradeoff: SBA loans involve more documentation and a longer approval timeline than equipment-specific financing.

Working capital loans

For operators who already own a truck but need funds for inventory, staff, marketing, or operational expenses, a working capital loan provides flexible short-term capital. 

Dimension Funding offers working capital loans with terms up to 24 months and repayment options on a daily, weekly, or monthly basis. These are particularly useful for bridging seasonal revenue gaps or covering an unexpected expense without disrupting operations.

What Lenders Look for in Food Truck Applications

Food truck lending involves the same core underwriting criteria as other equipment financing, with a few industry-specific considerations worth understanding.

Credit profile and time in business remain the primary factors. Startups under two years old face more scrutiny — the Federal Reserve’s 2025 Small Business Credit Survey found that businesses under two years old had a full-funding rate of just 28%, compared to 57% for businesses with ten or more years of history. Equipment financing partially offsets this disadvantage because the truck as collateral reduces lender exposure.

What else strengthens a food truck application

Two years in business is the preferred benchmark — but good credit can substitute for operating history for operators who don’t yet meet that threshold. A business plan with realistic revenue projections, a defined location strategy, and documented catering or event commitments all signal to lenders that the operator has thought through the business — not just the menu. 

For startups, demonstrating that you understand your cost structure (food cost percentages, permit requirements, commissary fees) matters as much as credit score.

New vs. Used Food Truck Financing

The new vs. used decision affects your loan amount, terms, and total cost of ownership — not just the purchase price.

New trucks qualify for the most favorable financing terms and longest repayment periods, and come with manufacturer warranties that reduce maintenance risk. Used trucks cost significantly less upfront, making them attractive for operators managing tight capital budgets. Lenders assess used trucks on age, mileage, equipment condition, and remaining useful life.

Tax treatment on food truck financing

Financing a food truck — new or used — opens up significant tax benefits. Under Section 179, businesses can deduct the full purchase price of qualifying equipment in the year it’s placed in service, per IRS Publication 946. For 2026, the deduction limit is $2,560,000. 

The One Big Beautiful Bill Act of 2025 also restored 100% bonus depreciation for qualifying property — including used equipment new to your business — placed in service after January 19, 2025. Consult a tax advisor to confirm how these deductions apply to your specific situation.

Hidden Costs to Budget for Before You Launch

The truck and equipment are the visible costs. These are the ones that surprise first-time operators.

Commissary fees run $300 to $1,200 per month in most cities. Insurance (general liability plus commercial auto) adds $2,000 to $6,000 annually. Fuel and propane run $200 to $800 per month, and maintenance should be budgeted at $200 to $800 monthly to avoid cash flow disruption from unexpected breakdowns. None of these appear in the loan amount — but all affect whether monthly payments stay manageable.

Financing Your Food Truck with Dimension Funding

Dimension Funding offers food truck financing for both startup and established operators, covering the truck purchase, kitchen equipment buildout, and associated costs in a single financing structure. Qualifying applicants can take advantage of no payments for 90 days (restrictions apply), giving new operators time to generate revenue before the first payment is due. Application-only financing is available up to $250,000 with no financial statements required, and most credit types are accepted — including first-time operators and applicants who’ve been declined by traditional banks.

Use the financing payment calculator on the food truck financing page to estimate monthly payments across 12, 24, 36, 48, and 60-month terms before you apply. Contact Dimension Funding to walk through financing options based on your specific truck, budget, and launch timeline — same-day decisions are available on qualifying transactions. 

Frequently Asked Questions

How much do I need to put down to finance a food truck? 

Down payment requirements vary by lender, credit profile, and whether the truck is new or used. Borrowers with strong credit may qualify for low or no down payment financing on qualifying transactions. First-time operators or those with limited business history should budget for 10–20% down. The truck itself serves as collateral, which often makes equipment financing more accessible than unsecured startup loans.

Can I get food truck financing as a startup with no revenue? 

Yes, though approval conditions are generally stricter for businesses under two years old. Equipment financing is typically more accessible for startups than conventional business loans because the truck reduces lender risk as collateral. Having a detailed business plan, a defined location strategy, and documented event or catering commitments strengthens a startup application.

What financing covers besides the truck itself? 

Equipment financing through Dimension Funding can cover 100% of associated costs on qualifying transactions — including kitchen equipment, installation, and buildout. Working capital loans can cover inventory, staffing, marketing, and operational expenses separately from the truck purchase.

Is an SBA loan better than equipment financing for a food truck? 

It depends on your situation. SBA loans offer longer terms and are well-suited for operators with solid credit and the patience for a more involved application process. Equipment financing approves faster — often same-day — requires less documentation, and uses the truck as collateral. Many operators use equipment financing for the truck and SBA microloans or working capital loans for operational startup costs.

What credit score do I need to finance a food truck? 

There’s no universal minimum. Dimension Funding accepts most credit types, including applicants who’ve been turned down by banks. Stronger credit profiles qualify for better terms and lower down payment requirements. Credit score is one factor among several — time in business, cash flow projections, and the asset being financed all factor into the decision.

Can I write off a financed food truck on my taxes? 

Yes. Section 179 allows businesses to deduct the full purchase price of qualifying equipment — including a financed food truck — in the year it’s placed in service, up to $2,560,000 for 2026. Bonus depreciation at 100% also applies to qualifying property placed in service after January 19, 2025, including used equipment new to your business. Work with a tax advisor to confirm eligibility and maximize your deductions.

What’s the survival rate for food trucks, and how does financing affect it? 

Approximately 60% of food trucks survive three or more years. Undercapitalization is consistently cited as the primary driver of early failure. Structuring financing to cover not just the truck but permits, equipment, working capital, and a cash buffer for the first 90 days significantly improves the odds of getting through the startup period intact.