
A restaurant can be packed in August and half-empty in January while paying the same rent, the same insurance, and nearly the same kitchen staff. The problem is not that the business is unprofitable. The strong months and the lean months simply do not line up with the bills. Dimension Funding has financed restaurant owners since 1978, and bridging the off-season is one of the most common reasons operators look for working capital.
Slow months are predictable, which means they can be planned for. Owners who map their off-season cash needs ahead of time can arrange a Dimension Funding working capital loan before the dip arrives, rather than scrambling once it does.
How Deep the Slow Months Really Are
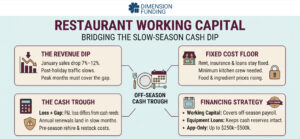
National data shows a clear seasonal pattern. According to Census Bureau data compiled by the Federal Reserve Bank of St. Louis, unadjusted sales at food services and drinking places fell from about $99.6 billion in December 2025 to about $92.2 billion in January 2026. That is a drop of roughly 7%, and January came in nearly 12% below August 2025’s $104.4 billion.
The January dip is a regular event. The National Restaurant Association’s analysis of Census data found that between 2017 and 2020, January’s unadjusted sales averaged 8.7% below the prior December. Beach towns, ski areas, and college towns often see far deeper drops than the national average.
Why Costs Don’t Fall With Sales
If costs dropped in step with revenue, slow months would be quieter but not tighter. In practice, a large share of a restaurant’s costs stays put.
Fixed Costs Set the Floor
The National Restaurant Association estimates that food and labor each account for about 33 cents of every sales dollar. It also reports that 33% of operators said their restaurant was not profitable in the first half of 2026. Food costs flex with covers, but labor flexes only partly, because a dining room still needs a minimum crew to open.
Rent, insurance, utilities, software subscriptions, and equipment payments do not flex at all. Those fixed costs set a floor that the slow months must still cover.
Input Costs Are Still Rising
The USDA Economic Research Service’s September 2026 Food Price Outlook forecasts beef and veal prices up 9.4% in 2026 and fresh vegetables up 5.7%. Menu prices cannot always keep pace, especially in the off-season, when guests are more price-sensitive and traffic is already down.
A Slow-Month Cash Map
The example below compares a peak month with a slow month for an illustrative full-service restaurant in a seasonal market. Food runs at 33% of sales in both months. Labor starts at 33% in the peak month but falls only partway in the slow month, because minimum staffing still applies.
Line Item | Peak Month | Slow Month |
Sales | $140,000 | $105,000 |
Food cost (33% of sales) | $46,200 | $34,650 |
Labor | $46,200 | $41,000 |
Rent | $14,000 | $14,000 |
Insurance, utilities, and other fixed costs | $12,000 | $12,000 |
Equipment and loan payments | $6,000 | $6,000 |
Monthly result | +$15,600 | −$2,650 |
A 25% drop in sales turns a $15,600 monthly surplus into a $2,650 shortfall. The strong months should cover the difference, but only if that cash is still available when the slow season arrives.
The Pre-Season Spend
The tightest point often comes at the end of the slow season. Before sales recover, many restaurants rehire and train staff, restock inventory for a new menu, and schedule repairs they postponed during the rush. Those costs arrive weeks before the busy season’s revenue does.
Annual bills can land in the same window. Insurance renewals, license fees, and property taxes often come due early in the year, stacking fixed obligations on top of the lowest sales months.
The Seasonal Loss Is Not the Same as the Cash Gap
A restaurant can have a seasonal operating loss without needing financing equal to that loss. The profit and loss statement measures profitability, while cash flow measures whether the business can pay its bills when they come due. SBA training on cash flow management explains why profitable businesses can still run into cash shortages and how to prepare for predictable slow periods.
Measuring cash over regular intervals helps show where the shortfall falls. The FDIC and SBA’s Money Smart for Small Business curriculum describes periodic cash flow measurement, monthly or quarterly, as a way to estimate a business’s future cash position.
The Seasonal Operating Loss
Consider a restaurant with these projected slow-month results.
Month | Operating Result |
January | −$2,650 |
February | −$3,000 |
March | −$2,350 |
Total | −$8,000 |
The $8,000 total is the seasonal operating loss, but it is not automatically the financing requirement. A restaurant that enters January with $20,000 in cash may absorb the losses without borrowing. A restaurant with only $3,000 available could run short in the first month, even with the same total projected loss.
Finding the Cash Trough
The more useful calculation is the cash trough: the lowest point your projected cash balance reaches. Build the projection from actual payment timing for payroll, rent, suppliers, taxes, loan payments, and other obligations, not just monthly revenue and expenses. Use the same months from the last two or three years as your baseline.
Month | Operating Result | Timing Items | Ending Cash |
Starting balance | $12,000 | ||
January | −$2,650 | Insurance renewal, −$6,000 | $3,350 |
February | −$3,000 | None | $350 |
March | −$2,350 | Pre-season restock and hiring, −$9,000 | −$11,000 |
Seasonal cash gap = minimum required cash balance − lowest projected cash balance. If this restaurant wants to keep at least $10,000 on hand for payroll, its gap is 10,000minus(-11,000), or $21,000. That is far more than the $8,000 operating loss, because timing items land in the same months. Sizing working capital around the actual amount and timing of the shortfall avoids both under-borrowing and borrowing more than the calendar requires.
Financing Timed to the Calendar
A working capital loan fits a defined seasonal gap once the cash trough is known. Arranged before the dip, it provides a set amount on a fixed schedule, so the owner knows the payment before the slow months begin. Short-term business loans can cover a narrower need, such as a large pre-season inventory order.
Equipment is a separate decision. A walk-in cooler or range that fails in February can wipe out the reserve meant for payroll. Restaurant equipment financing spreads replacement costs over fixed payments, and Dimension Funding offers application-only equipment financing up to $250,000 with no financial statements required. Funding typically arrives the same day or the next business day through DocuSign.
Keeping the Kitchen Open Through the Quiet Stretch
Seasonal swings are a normal part of the restaurant business. Project your cash month by month, find the trough rather than the total loss, and keep equipment replacements on their own financing so peak-season cash can carry operations through the dip.
Dimension Funding prefers businesses with two or more years in operation, though strong credit can substitute. To size financing around your restaurant’s actual cash gap, Contact Dimension Funding at 1-800-755-0585 or Sales@DimensionFunding.com.
Frequently Asked Questions
Should a seasonal restaurant close during its slowest weeks?
Some do, but rent, insurance, and loan payments continue while the doors are closed. Compare those costs against the shortfall of staying open, and include the cost of rehiring and retraining staff.
How do lenders view seasonal revenue?
Lenders typically compare the same months across several years rather than judging a single slow quarter. Twelve or more months of bank statements that show a repeating pattern help demonstrate that the dip is predictable.
Do holiday gift card sales help the slow season?
Gift cards sold in December bring in cash early, but redemptions often land in January and February. That brings in guests without new cash, so treat gift card balances as an obligation, not a reserve.
Should sales tax collected in busy months be treated as operating cash?
No. Sales tax collected during the peak is owed to the state on its filing schedule. Keeping it in a separate account stops it from masking your real cash position.
When is the best time to apply for financing?
Apply during or just after your strongest months, while recent bank statements reflect peak sales. Waiting until the slow season means applying with your weakest numbers on file.
Can off-season revenue reduce the gap?
Catering, private events, prix fixe menus, and holiday party bookings can add revenue in quiet weeks. Even modest bookings help cover the fixed-cost floor.
Should I renegotiate supplier terms before winter?
Longer payment terms from key suppliers during slow months can ease the gap. Suppliers are often more flexible when asked in advance than after a payment is missed.